Bioenergies and biomaterials

Carbon footprint and environmental requirements: the new strategic agenda that drives opportunities in bioenergies and biomaterials

Sustainability is at the heart of the global agro-industry agenda.

The main markets incorporate environmental standards that change trade access conditions, strengthen the traceability of production chains and expand demand for carbon information. This scenario incorporates new operational challenges and opens up investment opportunities linked to the bioeconomy.

Agro-industrial companies face a context where the ability to measure, document and communicate their environmental performance becomes strategically relevant. Carbon footprint management is gradually integrated into commercial, financial and productive decisions.

Environmental traceability strengthens export competitiveness

The European Union is making progress in implementing the Regulation on Deforestation Free Products (EUDR), a regulation that requires proof of the origin of certain raw materials and evidence that their production maintains specific environmental criteria. Soak, beef, wood, coffee, cocoa, palm oil and rubber are part of the initial scope of the regulation.

This process accelerates investments in georereference systems, digital traceability platforms, certifications and satellite monitoring. The quality of environmental information is beginning to be consolidated as a business asset with a direct impact on export continuity.

At the same time, other markets and large multinational companies incorporate their own sustainable supply policies, extending the scope of these requirements beyond official regulations.

The carbon footprint incorporates economic value into productive management

Emissions measurement is no longer an environmental indicator. Its use allows to identify energy efficiency opportunities, optimize processes, reduce operational costs and strengthen positioning against international customers.

Financial institutions also incorporate environmental criteria within their risk assessments, while many investment programmes prioritize projects with verifiable sustainability indicators.

This change promotes greater integration between production, technology and data management. Sensors, digital platforms, satellite images and artificial intelligence expand the ability to build reliable and auditable environmental indicators.

Agro-industrial waste drives new sources of income

One of the most relevant changes arises around the full use of biomass.

Agricultural waste, livestock effluent, forest by-products and industrial discards generate opportunities to develop bioenergy projects with the capacity to supply industrial processes, produce electricity, generate biogas or develop advanced biofuels. Argentina has specific programmes aimed at promoting the development of bioenergies and the use of agricultural biomass.

This development increases the potential profitability of historically underutilized assets and strengthens income diversification within agro-industrial enterprises.

Distributed generation, energy self-consumption and waste recovery consolidate a more efficient production model in resource use.

Biomaterials expand regional bioeconomy

The transition to materials of biological origin represents another of the great opportunities for agro-industry.

Bioplastics, plant fibres, biomaterials for construction, biodegradable packaging and biological-based chemicals expand the universe of applications derived from agricultural and forestry crops.

A number of countries increase investments to replace fossil inputs with renewable raw materials. This trend strengthens the development of higher value-added chains and promotes the articulation between agro-industrial companies, universities, technological centres and industrial manufacturers.

The availability of biomass places Latin America as a region with competitive advantages to supply this productive transformation.

The business strategy incorporates new decision variables

Sustainability is evolving towards a dimension linked to competitiveness, market access, financing and innovation.

Companies that develop capacities to measure emissions, strengthen traceability and value waste build relevant advantages against an international environment with higher environmental requirements.

Strategic planning incorporates decisions on certifications, technological investments, partnerships with specialized suppliers, integration of environmental data and development of new business models associated with the bioeconomy.

The convergence between agricultural production, renewable energy, circular economy and biomaterials extends the growth horizon for companies capable of integrating these capacities into their long-term strategy.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Solar panels: what variables today define the profitability of the energy business

Solar energy consolidates its position as a structural axis of the global energy transition.

The sustained fall in technological costs, along with regulatory pressure and corporate demand for clean energy, drives its adoption in multiple productive sectors.

Market growth has a more complex dynamic. The competitiveness of the solar business depends on financial, regulatory and commercial variables that have a direct impact on project profitability.

Falling from technological costs and market expansion

The reduction in the cost of solar panels over the last decade is one of the main drivers of the sector's growth. Reports from international agencies such as the International Energy Agency (IEA) and BloombergNEF show a sustained downward trend in the cost per watt installed.

This phenomenon extends access to solar solutions in industrial, commercial and residential segments. The increase in the global scale, led by China, consolidates an abundant and competitive offer.

Economic impact:
The reduction of CAPEX improves project viability and shortens investment recovery periods.

Strategic implications:
Companies face a market with lower entry barriers and greater price competition.

Regulatory volatility and pressure on business models

The regulatory environment plays a decisive role in the profitability of the sector. Changes in subsidy schemes, network injection rates and tax frameworks directly affect the income flow of solar projects.

In Latin America, regulatory heterogeneity generates different scenarios between countries. Markets such as Brazil and Chile advance in more stable frameworks, while others present policy uncertainty.

Economic impact:
The predictability of income flow becomes a critical variable for the financial structure of projects.

Common error:
To underestimate the regulatory risk in the investment assessment.

Strategic implications:
Companies prioritize markets with regulatory stability and design stronger contractual structures.

The role of financing in solar expansion

Access to finance defines the scale of growth in the sector. The participation of multilateral banks, investment funds and green financing mechanisms promotes the development of large-scale projects.

The cost of capital becomes a central variable. High interest rates impact profitability, especially in emerging economies.

Economic impact:
Financing conditions the viability of projects and defines the speed of expansion of the sector.

Strategic implications:
Companies seek more efficient financial structures and partnerships with institutional actors.

Storage integration and intermittent management

The incorporation of energy storage systems strengthens the solar energy value proposal. The batteries allow to manage intermittent and improve supply stability.

Technology development in storage is progressing rapidly, with cost reduction and efficiency improvements.

Economic impact:
The combination of solar generation with storage increases the value of the energy produced.

Strategic implications:
Hybrid projects gain relevance in energy-intensive industrial sectors.

Corporate self-consumption as a growth engine

Industrial and commercial companies adopt distributed generation solutions to optimize costs and reduce exposure to price variations.

Self-consumption is consolidated as an active energy strategy, aligned with sustainability and operational efficiency objectives.

Economic impact:
Reducing energy cost improves operational margins in consumer-intensive sectors.

Strategic implications:
Energy is integrated as a key variable in business competitiveness.

Increasing competition and the need for differentiation

The growth of the sector attracts new players, from developers to technological integrators. Competition intensifies and pressures margins.

The differentiation is built on technical capabilities, financing, operational efficiency and proposal of integral value.

Economic impact:
Competitive pressure reduces margins in standardized projects.

Common error:
To compete exclusively in price without developing strategic capacities.

Strategic implications:
Companies must define clear positioning and develop sustainable competitive advantages.

Strategic perspective for the sector

The solar panel market has a sustained growth trajectory with increasing complexity. Profitability depends on the ability to manage critical variables such as regulation, financing, technology and business model.

Companies operating in this sector are facing a scenario that requires strategic decisions in the medium and long term. Vertical integration, development of hybrid solutions and expansion to new demand segments appear as relevant lines of action.

Solar energy is placed as a structural component in the global energy matrix and in the operational strategy of companies.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


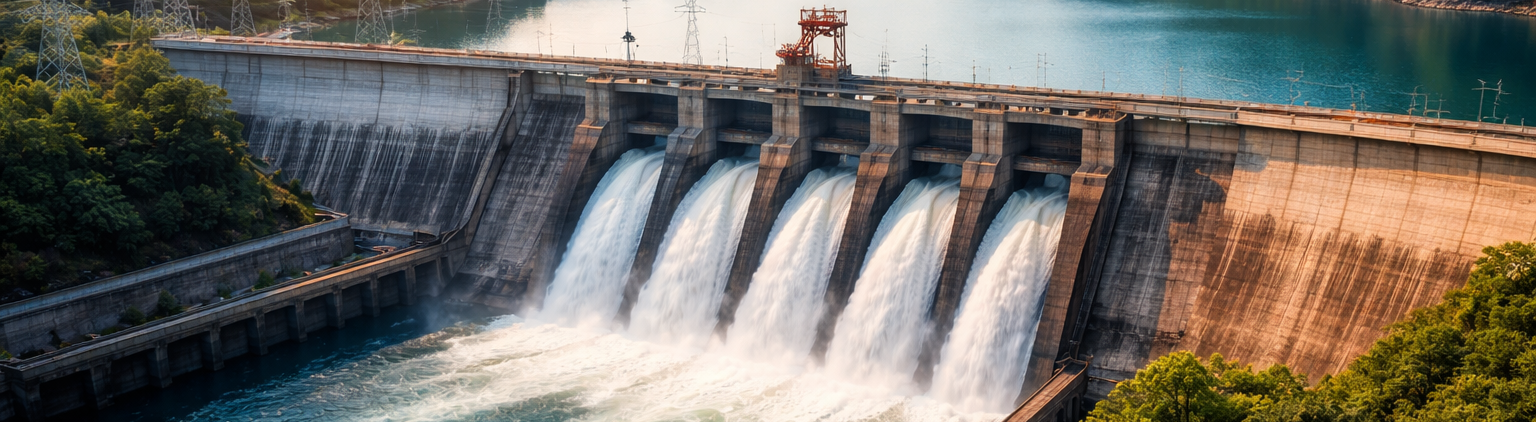
Hydraulic energy: the strategic asset that redefines the global energy transition

The global energy transition is moving towards a more diversified matrix where the stability of the electrical system takes on a central role.

In that context, Hydraulic energy consolidates its positioning as one of the most relevant sources to ensure continuous generation, storage and regulation of networks. The latest developments in investment, technological innovation and energy policy put hydroelectricity at a new stage of strategic expansion.

At the global level, agencies such as the International Energy Agency (IEA) and the World Bank point out that hydropower accounts for about 15% of the world's electricity generation and more than 50% of renewable electricity. This leadership is sustained on three key attributes: stable generation capacity, operational flexibility and extended asset life.

The current context introduces an additional dynamic. The acceleration of intermittent energies such as solar and wind drives the need for systems that bring stability. Hydroelectricity performs this function through reservoir plants and, in particular, through pumping storage systems (pumped storage), which allow the storage of energy at times of low demand and release it into consumption peaks.

Global expansion and new investment geography

China leads global hydroelectric development, concentrating more than 30% of installed capacity. Large-scale projects continue to expand their energy infrastructure with a focus on security of supply. India and South-East Asia also accelerate investments to sustain growth in electricity demand.

Latin America presents one of the greatest structural opportunities. Brazil, Colombia, Chile and Peru have significant water resources and an energy matrix where hydroelectricity already has a relevant weight. The strategic challenge is to modernize existing infrastructure, improve operational efficiency and manage climate risks.

Africa emerges as a region of high potential. The development of projects in the Congo and Nile basin opens up opportunities to expand electrification and attract international funding. Multilateral institutions promote these developments as part of sustainable growth agendas.

Technological innovation and digitization

The digitization of the hydroelectric sector is redefining the asset operation. Advanced artificial and analytical intelligence technologies make it possible to optimize the use of water resources, anticipate maintenance and maximize generation efficiency.

Real-time monitoring systems improve reservoir management against climate variability. This is critical in a scenario where extreme events, such as prolonged droughts or intense rains, have a direct impact on generation capacity.

Another relevant innovation is the development of hydroelectric microsystems. These solutions allow for decentralized generation in rural or industrial areas, expanding access to energy with less environmental impact and less infrastructure requirements.

Regulatory pressure and sustainability

The progress of the global environmental agenda redefines standards for hydroelectric projects. More stringent regulations require deeper environmental impact assessments, especially in relation to biodiversity, land use and local communities.

In Europe, green taxonomy sets specific criteria for classifying sustainable investments, which directly affects the financing of new projects. This framework promotes the development of projects with less environmental impact and greater efficiency in water use.

In emerging markets, international financial institutions make access to credit conditional on the adoption of environmental and social standards. This transforms the design and implementation of hydroelectric projects, incorporating sustainability criteria from early stages.

Structural risks: climate, financing and social leave

Climate change introduces a critical variable in hydroelectric planning. The variability in precipitation patterns affects the predictability of water resources, which directly affects the profitability of projects.

Funding also presents challenges. Hydroelectric projects require intensive capital investments and long recovery horizons. The global context of high interest rates increases the cost of capital and requires more sophisticated financial structures.

Social leave is consolidated as a determining factor. Local communities, environmental organisations and political actors influence the feasibility of projects. Stakeholders management takes on a strategic role at all stages of development.

Strategic perspective: the role of hydroelectricity in the energy system

Hydraulic energy plays a structural role in the energy transition. Its regulatory capacity makes this resource a key enabling force for the expansion of intermittent renewable energy.

Energy companies face a scenario where the optimization of existing assets generates competitive advantages. The modernisation of power plants, the incorporation of digital technology and integration with other renewable sources define market positioning.

Pump storage emerges as one of the most growing segments. This model allows the transformation of hydroelectric power plants into large-scale batteries, providing flexibility to the electrical system.

In Latin America, the strategic opportunity is focused on three areas: selective capacity expansion, operational efficiency and the development of climate-resilient infrastructure. The companies that integrate these factors into their strategy will be better positioned against the evolution of the global energy market.

Competitive dynamics and investment

Investment funds, multilateral banks and energy companies are increasing their exposure to the hydroelectric sector. The stability of cash flows and the relevance of the asset in the energy transition strengthen its attractiveness.

Interest on existing hydroelectric assets is growing in developed markets. The acquisition and modernization of power plants can capture value without taking on the risks associated with greenfield projects.

In parallel, vertical integration between generation, storage and distribution sets up new business models. This dynamic redefines competition in the energy sector.

Implications for companies and decision makers

The current scenario requires strategic decisions based on efficiency, sustainability and resilience. Energy companies are moving towards more flexible operating models, integrating multiple sources of generation.

Water resource management takes a strategic approach that combines technology, regulation and long-term planning. The ability to anticipate climate scenarios is translated into competitive advantage.

Positioning in international markets is also influenced by the ability to meet environmental standards and access sustainable financing.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.