The IA enters the business structure

What changes for companies according to Stanford?

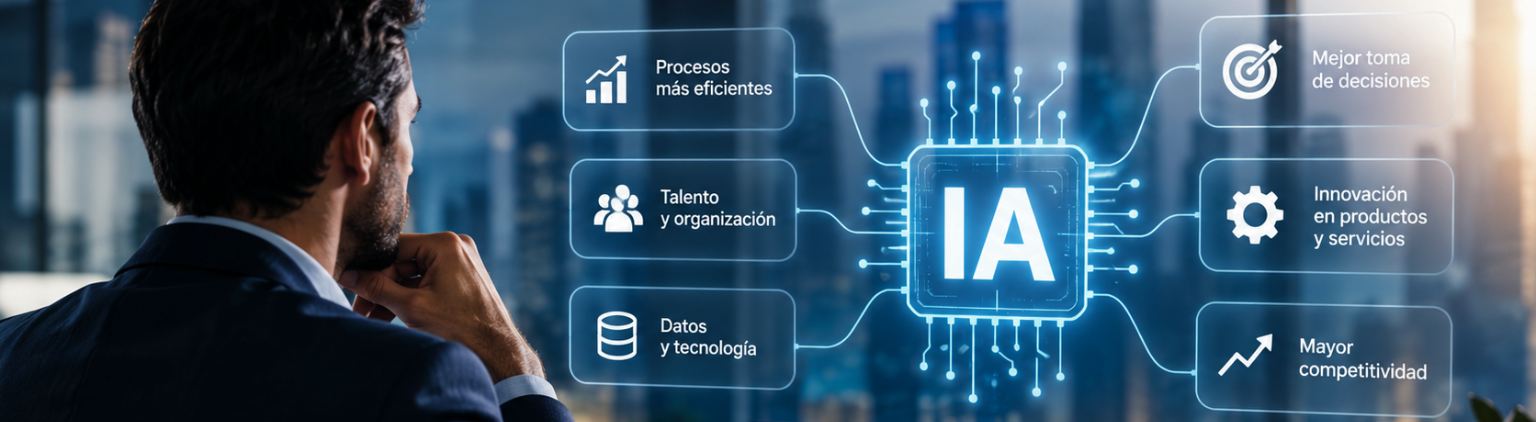
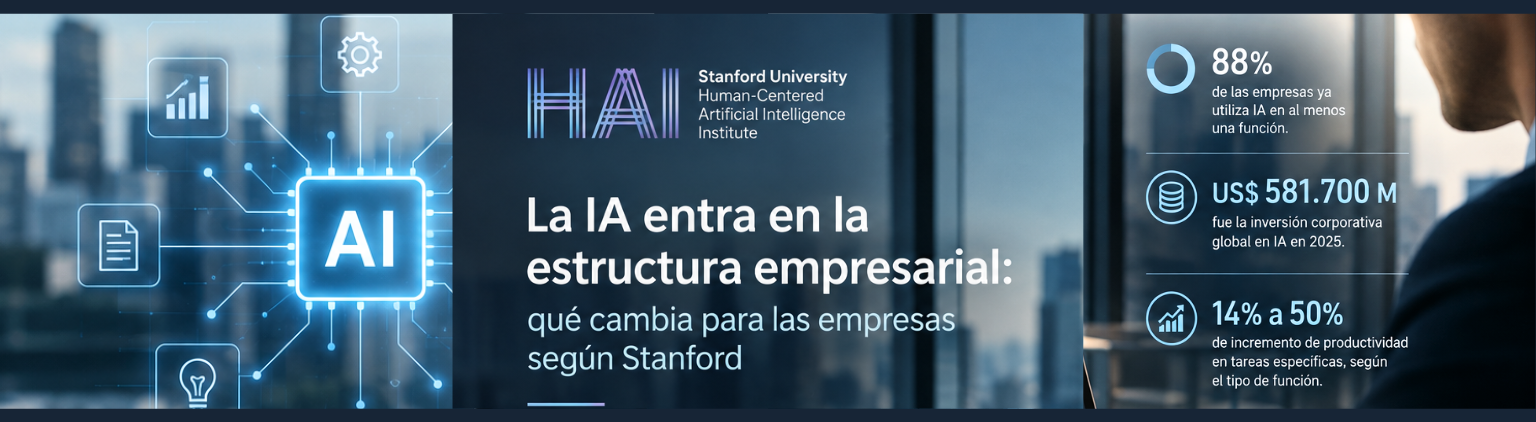
The AI Index 2026 shows that artificial intelligence became a structural place in the organizations. Business adoption reached 88%, global corporate investment reached US$581.7 billion and the first productivity effects appear more clearly in functions where work can be measured. For companies, the strategic challenge is to order where to apply IA, how to measure its impact and what internal capacities to develop.

Business adoption reached a structural scale

Artificial intelligence entered a new stage of business adoption.

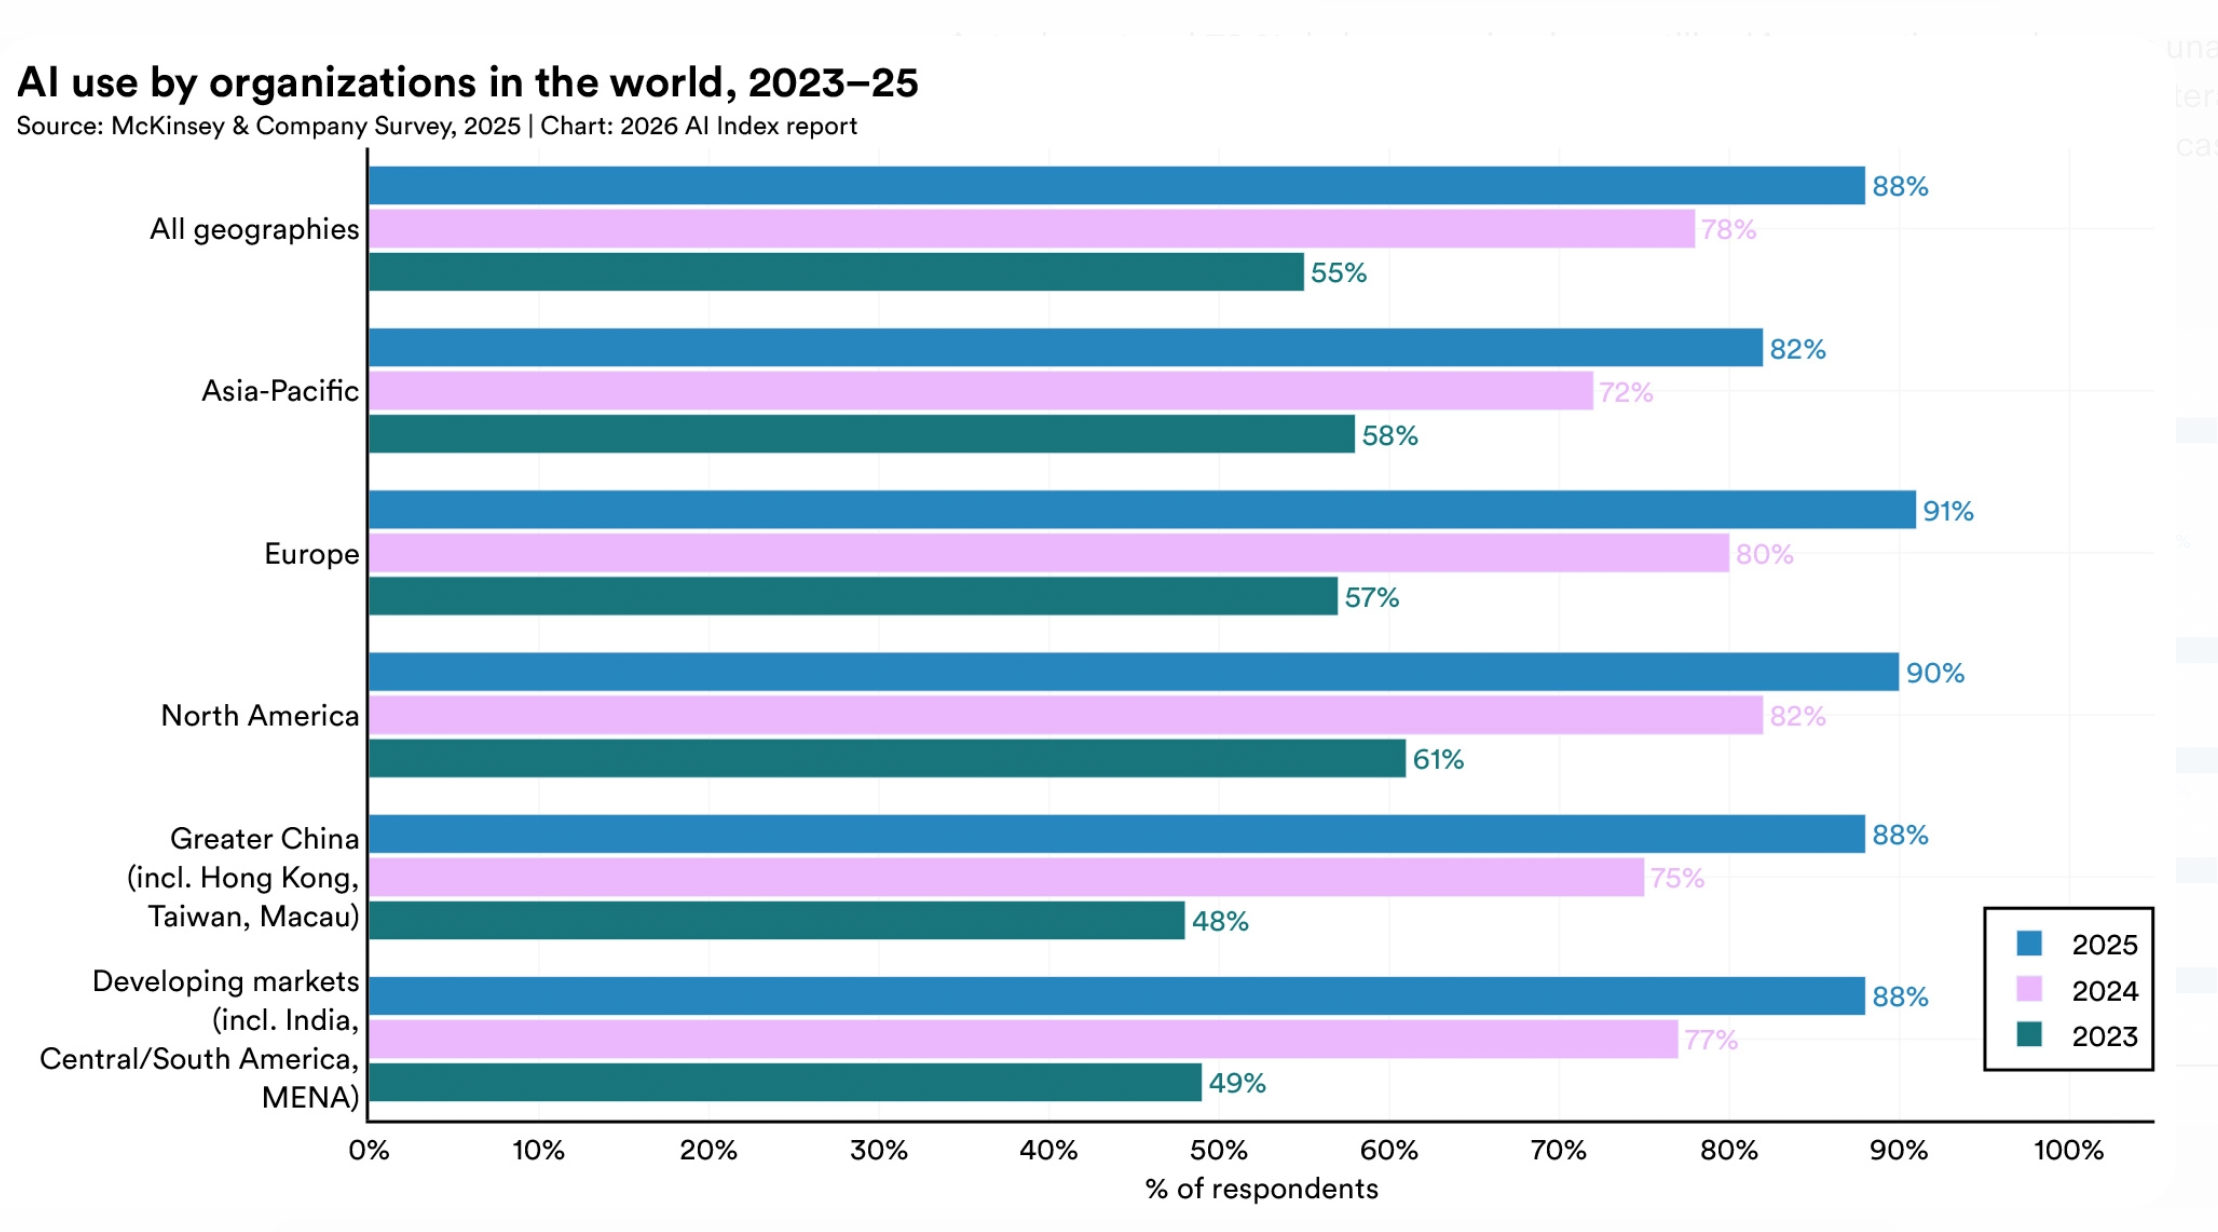
According to Stanford HAI Index 2026, 88% of the organisations surveyed reported using IA in at least one function during 2025, compared with 78% in 2025. In addition, more than half of the organizations reported using IA in three or more functions.

Generative IA also expanded its presence. 79% of the organizations surveyed reported using it regularly in at least one business function, compared with 71% of the previous year. China and Europe recorded some of the largest annual increases in adoption.

This evolution changes the business conversation. The central issue is the ability to integrate technology into specific processes, with defined economic and metric performance objectives.

For a CEO or commercial director, this involves reviewing where the IA can generate direct impact on income, costs, productivity and predictability.
Investment marks a new competitive scale

The volume of capital allocated to artificial intelligence confirms the economic dimension of this transformation.

Stanford estimates that global corporate investment in IA reached US$581.7 billion in 2025with a growth of 130% over the previous year. Private investment reached US$344.7 billion and grew 127.5%. The investment in generative IA increased by more than 200% and concentrated about half of private funding.

United States maintained a dominant position in private investment, with US$285.9 billion in 2025, compared to US$12.4 billion in China. Stanford warns that this comparison may underestimate the total volume of resources allocated by China due to the weight of public and state funds.

The investment dimension also appears in infrastructure. The major technology companies are strongly raising their capital costs to sustain computing capacity. Google, for example, reported more than US$150 billion capex per year in 2025.

For companies in other sectors, this investment scale has a specific consequence: the availability of IA tools will continue to expand and the relative cost of accessing advanced capacities will remain a strategic variable.

Productivity is beginning to be measured by function

One of the most relevant data in the report appears in the relationship between IA and productivity.

Stanford identifies increases from 14% and 15% in customer service, 26% in software development and 50% in marketing production. The greatest benefits appear in structured, measurable tasks with simple results to verify.

This point has a direct implications for management.

The productivity associated with IA can be more accurately analysed when the company breaks down its processes into specific activities. Attention to consultations, content generation, documentary analysis, programming, information classification and certain administrative tasks have favourable characteristics for this measurement.

The business decision requires identifying these functions before making extensive investments.

A company can have a high level of technological adoption and have a limited economic impact if the IA is incorporated without a precise definition of the process, indicator and expected result.

The commercial area enters a new stage of measurement

The productivity data in marketing is particularly relevant for B2B companies.

Content generation, commercial information analysis, account research, prospectus segmentation and certain commercial preparation tasks can incorporate IA tools within existing processes.

The strategic impact appears when these capabilities are connected to specific commercial variables: volume of opportunities, speed of response, cost of acquisition, account coverage, conversion and pipeline quality.

The IA can also expand the analytical capacity of commercial equipment working with large volumes of information.

The opportunity is linked to the structure of the business process. An organization with clear indicators can measure where technology generates productivity and where it requires process redesign.

Talent also begins to change

The adoption of IA has an effect on the composition of the teams.

The AI Index notes that labour impacts appear unevenly and more intensively in certain exposed groups and occupations. The use of software developers between 22 and 25 years of age fell by about 20% since 2024, while older workers experienced a different evolution. In addition, one third of the organizations surveyed expect to reduce their staff over the next year.

The data requires careful business reading.

The incorporation of IA modifies the combination of tasks, skills and professional profiles. For companies, this increases the importance of defining which functions require specialized knowledge, which activities can be automated and what new capacities must be developed internally.

Talent planning begins to be integrated with technology strategy.

Latin America faces an opportunity for selective adoption

The global expansion of the IA also opens an opportunity for Latin America.

Stanford shows that the adoption of generative IA reached 53% of the world's population in just three years. The rate of adoption has significant differences between countries and has a significant relationship with the level of income. At the same time, some markets reach higher levels than expected for their relative income.

The report also identifies Chile among the countries where IA's engineering capabilities are growing more rapidly.

For Latin American companies, this dynamic creates a scenario of increasing access to tools developed in leading markets.

The competitive advantage can arise from the ability to select applications with economic impact, integrate them into commercial and operational processes and build indicators to assess results.

The business priority goes by selecting where to capture value

Stanford's data show a simultaneous expansion of investment, adoption and productivity.

The strategic decision for companies is to translate this technological expansion into concrete priorities.

Three variables are of particular relevance:

1. Processes: identify activities where IA can generate measurable productivity.

2. Economy: to establish the impact on costs, income, margins and use of resources.

3. Structure: define responsibilities, internal capacities, indicators and investment criteria.

Technological adoption begins to form part of the business architecture. Value appears when the company can connect technology, processes and economic results within the same management logic.

The structure defines the ability to capture the value of the IA

The AI Index 2026 shows that artificial intelligence reached a significant business scale. 88% of the organizations surveyed already report some use of IA and global investment continues to grow at extraordinary rates.

For decision makers, the next challenge is linked to the ability to transform adoption into productivity, productivity into results and results into a sustainable business structure.

Artificial intelligence begins to function as a cross-sectional variable of competitiveness. Their impact will increasingly depend on the quality of the decisions accompanying their incorporation.

Vipzus accompanies in key production sectors in the diagnosis of opportunities, the management of their business structure and the definition of growth strategies. In a scenario where the IA modifies processes, capacities and investment criteria, strategic clarity takes on a central role in prioritizing opportunities and strengthening business predictability.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


The adoption of IA enters a stage of scale

Artificial intelligence is entering a stage in which the main business question goes through the ability to turn technological adoption into economic impact. The advantage begins to depend on how companies reorganize processes, talent, investment and decision-making around the IA.

The adoption of IA enters a stage of scale

Business adoption continues to accelerate. According to AI Index 2026 of Stanford, 88% of the organizations surveyed use IA in at least one function, while the generative IA is already present in at least one business function in 70%. At the same time, the use of IA agents remains at an early stage in most functions.

McKinsey finds a similar signal: almost nine out of ten participants use IA regularly in some function and 44% claim that their organization is carrying the IA on a business scale, compared to 38% of the previous year. In large companies, the proportion is 54%.

The strategic signal is clear: The IA is moving from being a tool used by individuals to becoming a capacity that begins to affect the full architecture of companies.

This movement has a direct consequence for decision makers: the relevant question goes by identifying where the IA can change revenue, costs, productivity, trade speed and decision-making capacity.

Individual productivity needs to become a business result

One of the central market tensions appears between adoption and capture of value.

McKinsey points out that companies are achieving individual productivity benefits while seeking to move them to sustainable financial results. His research suggests that the capture of value requires organizational changes that accompany the incorporation of IA.

Deloitte comes to a convergent conclusion: only 34% of the organizations surveyed claim to be really rethinking their business from the IA.

This places a strategic variable in the foreground:

The productivity generated by IA needs to be connected to specific economic indicators.

For a B2B company, these indicators may include:

  • Cost of purchasing customers;
  • Trade cycle speed;
  • Pipeline conversion;
  • Margin per client;
  • Response time;
  • Operational cost per transaction;
  • Recurrence;
  • Productivity per employee;
  • Launch speed of new services.

Technology is of business relevance when it changes these variables.

IA agents may alter the work structure

The next stage is linked to the AI agents, systems capable of performing tasks and processes with different degrees of autonomy.

McKinsey has a significant growth in the use of agents, especially among large companies: 40% of respondents from companies with incomes above US$One billion states to be climbing IA agents, compared to 27% of the previous year.

Deloitte here identifies one of the main organizational challenges. His research points out that approximately 75% of the executives consulted consider that their operating model will have to change over the next 12 to 18 months to support the expansion of IA.

The change may affect functions such as:

  • Commercial: research of prospects, preparation of proposals, monitoring and analysis of opportunities.
  • Marketing: content production, segmentation, audience analysis and customization.
  • Finance: analysis of information, forecasting and detection of anomalies.
  • Operations: planning, documentation, coordination and impact management.
  • Technology: software development, testing, documentation and maintenance.

The strategic consequence is relevant: the company begins to need a work architecture where intelligent people and systems share tasks, information and decisions.

The real challenge appears in the processes

Deloitte identifies one of the main barriers to scaling agents: organizations often try to automate processes originally designed for people. His report claims that only 11 per cent of organizations had successfully deployed IA agents in production at the time of their investigation.

This has a direct reading for the business strategy.

A fragmented business process, for example, can be partially automated by IA. Automation can accelerate individual tasks while maintaining the original structure of a process that has multiple friction points.

The opportunity appears when the company first analyses:

  1. What process generates value;
  2. Where repetitive work is concentrated;
  3. What decisions require a human approach;
  4. What information is available;
  5. What tasks can be delegated to systems;
  6. What indicators can measure the result.

This diagnosis makes it possible to define where the IA has a real capacity to generate impact.

Investment in IA increases and also increases the demand for return

Global investment confirms that transformation has a growing economic dimension.

Stanford estimates that global corporate investment in IA more than doubled during 2025. Private investment grew 127.5%, while generative IA concentrated almost half of the private funding related to IA.

This expansion is also increasing expenditure on infrastructure. Companies need computer capacity, storage, data, security and technological architecture to sustain increasing IA loads.

Deloitte warns that the increase in use can exceed the reduction in unit processing costs, creating increasing pressure on infrastructure and technology budget.

This is why a new management variable appears:

The return on investment in IA needs to be assessed at process and economic unity level.

Governance becomes a business variable

The progress of self-governing actors also increases the importance of governance.

Deloitte points out that only one in five companies has a mature model of governance for self-employed actors.

The challenge involves:

  • Access to sensitive information;
  • Permissions;
  • Tracability;
  • Security;
  • Human monitoring;
  • Protection of intellectual property;
  • Regulatory compliance;
  • Responsibility for automated decisions.

The regulatory discussion is also gaining intensity. In the United States, for example, legislators are driving new security rules and controls for advanced IA systems.

For companies, this makes IA governance a strategic management dimension linked to risk, reputation and operational continuity.

Latin America can capture value from business efficiency

For Latin America, the scenario presents an opportunity especially linked to productivity.

Companies in the region operate in markets where trade efficiency, the availability of specialized talent and the scale can condition growth. The IA can reduce certain information costs, speed up processes and allow relatively small teams to manage more activity.

The strategic point is in the selection of use cases.

Companies can prioritize applications related to:

  • Demand generation → identification and prioritization of prospects.
  • Sales → pipeline analysis, proposals and follow-up.
  • Service → automation of queries and classification of requirements.
  • Operations → planning, documentation and coordination.
  • Address → information analysis and decision support.

This logic is particularly relevant for B2B companies, where the quality of the business process is directly related to predictability and revenue.

The competitive advantage begins to depend on the reorganisation capacity

The evidence available points to the same direction: the adoption of IA grows rapidly, as organizational transformation advances at a more heterogeneous rate.

McKinsey notes that organizations are moving towards a larger scale of implementation. Deloitte simultaneously identifies a gap between strategic and operational preparation.

For CEOs and business directors, this puts five decisions at the heart of the agenda:

  • 1. Prioritize processes with measurable economic impact.
  • 2. To define which tasks remain under human responsibility.
  • 3. Build a data architecture to scale IA.
  • 4. Measure economic return by use.
  • 5. Design a commercial and operational structure prepared to work with intelligent systems.

The business transformation led by IA begins to acquire a structural dimension. Technology is a part of change. The organization, processes, talent, investment and indicators determine the ability to capture value.

The strategic agenda for the next 12 to 24 months

For business decision makers, the agenda can be organized around four questions:

Where it generates value the IA.
Identify processes where there is a clear relationship between automation, productivity and economic impact.

What structure the company needs.
Review internal processes, responsibilities, technology and capacities.

What investment each initiative requires.
Measuring infrastructure, talent, integration, security and recurrent costs.

How the result will be measured.
Link each implementation with income, margin, productivity, speed or predictability.

The IA is moving towards a phase in which business transformation capacity begins to be as relevant as technological capacity. Organizations that develop mechanisms to convert smart tools into measurable business improvements will be better prepared to capture the economic value of this new stage.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Customers, channels or markets

What risk does it pose for your company to depend on the same customers, channels or markets as usual?

The expansion of the technology sector maintains a sustained pace driven by artificial intelligence, automation and digitization of business processes.

In this scenario, many technology companies continue to grow on a commercial basis concentrated on a small set of customers, procurement channels or geographical markets. This concentration conditions business stability and limits the ability to sustain growth in the medium term.

Technology companies often develop long-term relationships with strategic customers. This model provides recurrent income and strengthens sectoral experience. At the same time, it increases exposure to any change in investment priorities, budgets or strategies of such clients.

Trade concentration increases business vulnerability

A concentrated portfolio amplifies the financial impact of each decision made by a relevant client. The cancellation of a contract, the reduction of the technological budget or a change of supplier may affect revenue, cash flow and investment capacity in innovation.

This scenario also conditions financial planning. Predictability depends on a limited number of external decisions, making it difficult to project growth more stable.

Traditional channels reach a point of maturity

Many technological companies built their growth through references, personal networks or historical alliances. These channels maintain strategic value, although they have limits to support expansion processes.

The B2B purchase process evolves towards digital routes where buyers investigate suppliers, compare solutions and use artificial intelligence tools to evaluate alternatives before first commercial contact. Visibility in different channels begins to directly influence the generation of opportunities.

Organizations that develop multi-channel strategies strengthen their ability to capture demand from different points of contact and reduce the dependence on a single business source.

Diversification strengthens trade predictability

Diversifying means expanding the commercial scope through new segments, industries, regions or marketing models. This strategy distributes risk and generates a more balanced income structure.

The incorporation of new markets also provides valuable information on emerging needs, strengthens innovation capacity and expands the competitive potential of the company.

Technology companies with structured business processes have better tools to identify opportunities, prioritize investments and manage sales cycles more accurately.

Expansion requires structure and priority criteria

Entering new markets requires informed decisions. The selection of segments, the value proposal, the commercial capacity and the resources available determine the feasibility of each initiative.

Sustained growth depends on a diagnosis to identify where there is the greatest potential for profitability, which channels have the best prospects and which customers contribute to building a more balanced portfolio.

The organizations that incorporate these criteria strengthen their resilience to economic, technological and competitive changes.

Strategic direction defines growth capacity

The development of the technological market increases the importance of regular review of the composition of the client portfolio, income distribution and the diversity of commercial channels. This assessment allows for the identification of concentration levels that could limit the future development of the company.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Global real estate investment

Data centers capture a growing share of global real estate investment

The expansion of artificial intelligence, the growth of data processing and the demand for digital infrastructure drive a new stage for the real estate market.

Data centers concentrate capital, change location criteria and generate opportunities for developers, investors and emerging markets.

Digital infrastructure is at the heart of the investment agenda

The real estate market is undergoing a transformation driven by the digital economy. The expansion of generative artificial intelligence, the growth of cloud computing and the multiplication of data-based applications increase the need for global technological infrastructure.

In this context, data centers are consolidated as one of the most demanded assets by institutional investors, infrastructure funds and specialized developers. Several international reports from PwC, Urban Land Institute and large investment firms place these assets among the main opportunities in the real estate sector for the coming years.

The demand comes from technology companies, cloud operators, streaming platforms, telecommunications companies and organizations that require increasing processing and storage capabilities.

The growth of digital traffic makes data centers an essential component for the functioning of the contemporary economy.

Energy availability becomes a strategic variable

The location of a real estate asset remains relevant, although the selection criteria evolve rapidly.

The ability to access reliable, scalable and competitive energy is of crucial importance for the development of new projects.

Large operators seek regions that can ensure stable power supply, high-capacity connectivity and favourable regulatory conditions for long-term investments.

This scenario drives a new logic of soil recovery. Land that historically had limited appeal for traditional developments begins to attract interest when they offer adequate energy infrastructure.

Urban and energy planning is beginning to have a direct impact on the real estate competitiveness of cities and regions.

Capital flows migrate to assets linked to the digital economy

Global real estate markets go through a more rigorous selection stage by investors.

The high interest rates in recent years have led to a thorough review of the criteria for capital allocation. The funds seek assets with structural demand, long-term contracts and prospects for sustained growth.

Data centers have much of these characteristics.

The expansion of artificial intelligence expands the need for computer capacity, as companies accelerate the digitization of processes, services and operations.

This dynamic generates a constant flow of demand that strengthens the financial attractiveness of these developments to other traditional market segments.

The consequence is visible: an increasing share of global real estate capital is directed towards technological infrastructure.

Latin America begins to win the role of the regional map

The region has conditions that begin to attract the attention of international operators.

Brazil, Mexico, Chile and Colombia concentrate much of the projects announced in recent years. The combination of digital growth, expansion of the consumption of technological services and the need for regional infrastructure drives new investments.

The Latin American market still has levels of development below those observed in the United States, Europe and Asia, which expands the long-term growth potential.

Cities that manage to strengthen their energy infrastructure, improve connectivity and provide predictable regulatory frameworks can capture a significant part of this expansion process.

For real estate developers, funds and infrastructure-related actors, the evolution of this segment represents a relevant opportunity to diversify portfolios and access markets with strong growth potential.

New challenges for developers and real estate investors

The development of data centers requires different capacities than conventional real estate assets.

The risk assessment incorporates energy, technological, regulatory and operational variables. Investment processes require a deeper understanding of digital infrastructure and the technological trends that drive demand.

The relationship between real estate, energy and technology is becoming increasingly integrated.

This convergence expands the need for strategic planning to identify competitive locations, understand demand developments and prioritize long-term vision investment opportunities.

Decisions made over the next few years will have a direct impact on the ability to capture value in one of the most growing segments within the global real estate market.

The technological infrastructure drives a new stage for the real estate

Data centers represent one of the most visible expressions of the convergence between digital economy and real estate investment.

The expansion of artificial intelligence, exponential data growth and the need for critical infrastructure strengthen the attractiveness of these assets for institutional investors and specialized developers.

The evolution of the sector opens up new opportunities for markets that can provide energy, connectivity and stability for large-scale projects.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Software consolidation

Strengthening the business software market: why medium-sized enterprises become strategic assets

The global business software market is undergoing an accelerated consolidation stage.

Investment funds, large technological groups and specialized companies intensify acquisitions aimed at capturing portfolio, intellectual property, sectoral positioning and commercial capacity.

The dynamics especially affect medium-sized B2B, SaaS and technology services with a consolidated technical trajectory and still immature business structures.

The phenomenon responds to a profound change in the priorities of the sector. The market began to value predictability, profitability and specialization more intensively than disorderly growth driven exclusively by user expansion or capital investment.

Profitability and recurrence gain strategic weight

For more than a decade, much of the technological ecosystem operated under models oriented to accelerated growth, geographical expansion and rapid market capture.

The global financial scenario introduced new priorities.

The increased cost of capital, margin pressure and increased investment selectivity strengthened criteria related to:

  • Recurrence of income.
  • Contractual stability.
  • Pipeline quality.
  • Commercial efficiency.
  • Customer concentration.
  • Cost-effective expansion capacity.

Companies with recurrent income, clear sectoral niches and efficient operating structures began to attract greater interest from strategic buyers and investors.

Business software is consolidated as critical infrastructure for multiple industries. This condition strengthens procurement processes aimed at integrating solutions, expanding ecosystems and ensuring competitive positioning.

Medium-sized enterprises concentrate procurement opportunities

The consolidation finds a particularly fertile ground in specialized medium-sized companies.

Many companies developed solid products, experienced technical equipment and in-depth knowledge of certain sectors. At the same time, they have limitations linked to trade scale, international positioning or regional expansion capacity.

This profile creates strategic opportunities for actors with greater financial capacity and consolidated trade structure.

Acquisitions make it possible to accelerate:

  • Portfolio expansion.
  • Access to specific segments.
  • Technological integration.
  • Sectoral specialization.
  • Regional coverage.
  • Advisory capacity.

In sectors such as logistics, health, retail, energy and agro-industry, vertical solutions become increasingly relevant within corporate strategies.

Specialisation begins to function as a value multiplier.

Consolidation changes technological competence

Market concentration causes structural changes over competitive dynamics.

The larger companies strengthen investment capacity, expand product ecosystems and improve service integration. Medium-sized enterprises face an environment of greater trade pressure and a need for strategic differentiation.

The competition is gradually moving from isolated functionalities to integral models of solution.

Corporate customers prioritize suppliers capable of offering:

  • Operational continuity.
  • Technological integration.
  • Financial stability.
  • Scalable support.
  • Sectoral vision.
  • Long-term accompanying capacity.

Technical positioning remains relevant, although commercial and strategic capacity gains influence on purchase decisions.

The value of the software moves towards sectoral knowledge

One of the most relevant changes on the market appears in the recovery of industry-specific knowledge.

Technology companies with operational understanding of certain sectors develop competitive advantages that are more difficult to replicate.

Solutions designed for logistics, manufacturing, health or agro-industry incorporate particular processes, indicators and needs that strengthen entry barriers.

The market awards companies capable of combining:

  • Technological development.
  • Customer's economic reading.
  • Operational understanding.
  • Advisory capacity.
  • Regulatory knowledge.
  • Sectoral adaptation.

Verticalization improves trade efficiency and strengthens the construction of authority within the market.

Latin America accelerates concentration processes

The region is undergoing a relevant transformation stage within the technological ecosystem.

The growth of business digitization, automation and applied artificial intelligence expands opportunities for expansion. At the same time, competition increases by scale, positioning and financing capacity.

Regional and international funds observe opportunities for companies with:

  • Consolidated corporate portfolio.
  • Recurrent income.
  • Sectoral specialization.
  • Low international penetration.
  • Trade structure in development.

In many cases, the main limitation to scaling appears in the commercial and strategic organization rather than in technical capacity.

Market consolidation also promotes alliances, mergers and integration agreements between medium-sized companies seeking to gain volume and competitive capacity.

The commercial structure becomes a valuation factor

The current dynamics change the way in which the value of a technology company is evaluated.

Pipeline quality, trade predictability and income stability take strategic weight within investment and procurement processes.

Companies capable of demonstrating:

  • A consistent generation of opportunities.
  • Clear commercial segmentation.
  • Low dependency on individual customers.
  • Positioning defined.
  • Contractual recurrence.
  • Cost-effective expansion.

They strengthen their capacity for negotiation and growth.

The technological market enters a stage where the business structure begins to have a direct impact on business valuation.

The ability to order expansion, build predictability and develop sectoral positioning becomes relevant within global technological competitiveness.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Cybersecurity and technology

Cybersecurity becomes a structural axis of digital business

The expansion of artificial intelligence, automation and connected platforms is changing the risk structure of technology companies and all digital production sectors.

Cybersecurity began to be central to strategic decisions linked to operational continuity, corporate reputation and financial predictability.

The global market is going through a stage where digitization advances on critical operations, industrial infrastructure, commercial management and supply chains. This process extends the area of exposure to computer attacks, data theft, operational interruptions and systemic vulnerabilities.

The evolution of the digital business is driving a change of criterion in directories and executive teams: computer security went from a technical function to a structural variable of the business.

Automation Expands Business Operational Risk

The accelerated incorporation of artificial intelligence and automation generated a massive expansion of connected devices, platforms and processes. This dynamic increases access points and operational complexity.

Attacks on logistics chains, financial platforms, industrial systems and SaaS companies began to show a growing economic impact on income, reputation and operational continuity.

According to recent reports from Deloitte and international agencies specialized in cybersecurity, threats related to generative IA, Ransomware and automated attacks are increasing speed and sophistication in global markets.

The situation is becoming more sensitive in Latin America, where many companies maintain fragmented technological structures, low level of integration and reactive security policies.

The exposure increases especially in companies that grew rapidly during digitization and commercial expansion processes without consolidating a robust protection and monitoring architecture.

The economic cost of a digital interruption gains scale

The growing dependence on digital platforms is raising the financial impact of any operational interruption.

A fall in infrastructure, an attack on sensitive data or a vulnerability in critical systems can simultaneously affect:

  • Facturing.
  • Logistics.
  • Customer service.
  • Corporate reputation.
  • Regulatory compliance.
  • Relationship with investors and partners.

The problem ceased to focus only on technical recovery. The current impact involves a deterioration of confidence, loss of contracts and increased operating cost.

The sectors with distributed operations and high digitization show greater sensitivity:

  • Logistics.
  • Energy.
  • Retail.
  • Financial services.
  • Cheers.
  • Industrial manufacturing.
  • Technology platforms B2B.

In these markets, operational continuity became part of the competitive positioning.

Artificial intelligence accelerates threat sophistication

The evolution of generative artificial intelligence is also changing the global cybersecurity scenario.

The new models make it possible to automate attacks, develop more precise phishing campaigns and increase the capacity to escape traditional protection systems.

In parallel, companies are using IA for predictive monitoring, early threat detection and automated vulnerability analysis.

The technological market is beginning to consolidate a new competitive career linked to self-security and real-time response capacity.

Large global technology companies are increasing investment in security infrastructure, cloud protection platforms and IA-driven defence systems. The strategic priority is focused on operational resilience and protection of critical digital assets.

Regulation begins to raise business standards

Regulatory pressure also began to intensify.

The United States, Europe and different Asian markets are making progress in regulatory frameworks linked to data protection, critical infrastructure and corporate responsibility for digital incidents.

Regulatory requirements begin to impact on:

  • Corporate reporting.
  • Technology audits.
  • Data management.
  • Operational traceability.
  • Relationship with technology providers.

This dynamic creates additional pressure on medium-sized enterprises and organizations with decentralized technological processes.

Cybersecurity is beginning to be integrated into decisions related to compliance, financing, corporate insurance and investment risk assessment.

Digital predictability becomes a competitive advantage

Technology companies and digitalization-intensive sectors face a new competitive demand: to sustain resilient and predictable operations in high digital exposure environments.

The ability to anticipate risks, monitor vulnerabilities and respond quickly to incidents begins to influence:

  • Profitability.
  • Trade stability.
  • Reputation.
  • Expansion capacity.
  • Market value.

The market begins to award organizations with integrated technological structures, clear protocols and strategic digital risk management capacity.

The evolution of the sector shows a growing convergence between technology, operational continuity and corporate strategy.

Cybersecurity is now directly associated with business sustainability and long-term competitiveness.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Global competition for semiconductors and technological sovereignty: the new axis of economic power

The semiconductor industry was consolidated as a central strategic asset in the global economy.

The acceleration of digitization, the growth of artificial intelligence and the expansion of technology-intensive industries position chips as a critical input for the competitiveness of countries and companies.

Disruption in supply chains during the pandemic and geopolitical tensions between the United States and China led to a technological sovereignty agenda in major economies. Governments and corporations activated investment plans, subsidies and industrial policies aimed at ensuring access, local production and control over key technologies.

Industrial geopolitics and critical chain control

The domain of semiconductors defines the capacity for innovation in sectors such as automotive, defence, telecommunications and consumer electronics. Global production has a high geographical concentration, with Asia leading advanced manufacturing, especially in Taiwan and South Korea.

The United States strengthened its strategy through the CHIPS and Science Act, with over $50 billion to encourage local production and reduce external dependence. Europe activated the European Chips Act with similar objectives, seeking to double its share in global production by 2030.

China, for its part, increased its state investment to develop domestic capacities and reduce technological constraints imposed by the West. This dynamic is a scenario of structural competition between economic blocs.

Record investment and state subsidies

The volume of investment in semiconductors reached historical levels. Leaders such as Intel, TSMC and Samsung announced plant expansion plans in the United States, Europe and Asia, driven by tax incentives and direct subsidies.

According to estimates by McKinsey and Deloitte, the industry will exceed $1 billion in annual income by 2030, with artificial intelligence-driven growth, electric vehicles and high-performance computing.

The production capacity becomes a strategic variable. The construction of fabs requires investments of more than USD 10 billion per plant, as well as specialized talent and robust technological ecosystems.

Asia, the United States and Europe in a race for technological autonomy

Taiwan maintains a dominant position in the manufacture of advanced chips, with TSMC as a central actor. South Korea, through Samsung, holds a strong presence in advanced memory and logic.

The United States is moving forward in industrial relocation with investments in Arizona, Texas and Ohio, while strengthening restrictions on technological exports to China.

Europe prioritizes the attraction of global manufacturers and the development of its own capacities, with Germany and France as emerging industrial poles.

Global competition is organized around access to technology, talent, intellectual property and financing. Each block builds its strategy with a focus on resilience and autonomy.

Impact in Latin America and strategic opportunities

Latin America is a limited participant in the semiconductor value chain. The region presents opportunities in segments such as assembly, testing, technological services and provision of critical minerals.

Countries with lithium, copper and other strategic inputs become relevant in the new technology map. The public-private sector articulation defines the ability to capture value in this transformation.

Companies in the region face an environment where access to technology and components directly impacts on costs, production and competitiveness. Strategic planning incorporates geopolitical and supply variables as critical factors.

Strategic perspective

The semiconductor industry sets a new standard of global competitiveness. Companies need to develop diversified supply strategies, technological alliances and adaptive capacity to changing regulatory environments.

Integration into global value chains requires investment in talent, innovation and industrial capacities. The location of operations and the proximity to technological hubs become more relevant.

Technological sovereignty results in critical process control, access to knowledge and sustained innovation capacity. Strategic decisions in this sector have a direct impact on the competitive position of companies and countries.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


IA - Enterprise infrastructure

Generative artificial intelligence: from technological experiment to business infrastructure

The new stage of artificial intelligence in companies.

In recent months, the artificial, generative intelligence has begun to be consolidated as a key technology infrastructure within organisations.

What was initially perceived as an experimental tool to generate texts, images or code is evolving into a platform that allows automate processes, optimize decisions and redesign operating models.

Companies in multiple sectors are incorporating these technologies in areas such as customer care, marketing, data analysis and software development. The result is a gradual transformation of the way organizations produce, manage information and make decisions.

Recent reports from McKinsey and Deloitte indicate that generative artificial intelligence could generate billions of dollars in global economic value in the next decade, promoting a new phase of digital transformation.

From pilot projects to operational integration

In the first stage, many companies adopted the artificial, generative intelligence through internal experiments and tests. Technology teams explored their capacities through pilot projects aimed at improving productivity or reducing costs in specific tasks.

However, recent market developments show a significant change: technology is beginning to be integrated into Central operating processes.

The main applications include:

  • Automation of customer care through intelligent assistants.
  • Content generation and marketing campaign optimization.
  • Development of software assisted by artificial intelligence.
  • Advanced data analysis for decision-making.
  • Optimization of internal processes.

This transition marks the step of technological experimentation towards a model in which artificial intelligence works as a cross-border digital infrastructure.

A global technological career

The advance of artificial intelligence is also driving a international technological competence.

The United States maintains a dominant position thanks to its technological ecosystem and the investment of large companies in artificial intelligence infrastructure. At the same time, China and the European Union have accelerated their investments in data centres, semiconductors and development of advanced models.

Global competition is concentrated in three key areas:

  • Development of large-scale artificial intelligence models.
  • Advanced computing infrastructure.
  • Access to large volumes of data.

In this context, artificial intelligence is becoming a strategic assets for both companies and national economies.

Regulation and technology governance

As artificial intelligence is integrated into business processes, the interest of regulators in establishing policy frameworks is also growing.

The European Union has made progress in developing the AI Act, one of the first regulatory frameworks to establish standards of transparency, safety and risk control in artificial intelligence systems.

Other countries are evaluating similar regulations, especially in areas related to:

  • Use of data.
  • Algoritmic sessions.
  • Responsibility for automated decisions.
  • Labour impact of automation.

For companies, regulatory development becomes a key factor in defining technology adoption strategies.

Strategic implications for enterprises

Generative artificial intelligence offers relevant opportunities to improve productivity and competitiveness, but its impact will depend to a large extent on how companies integrate technology into their business models.

The organizations that can capture the most value will be those that can combine technological innovation with organizational transformation.

This involves developing new capacities in:

  • Data analysis.
  • Process automation.
  • Technology management.
  • Specialized talent training.

At the same time, companies should manage risks associated with the adoption of artificial intelligence, including technology dependence, data security and regulatory compliance.

Perspective for Latin America

In Latin America, the adoption of artificial generative intelligence is still at an early stage, although some sectors are already exploring its potential.

Banking companies, retail, telecommunications and logistics are incorporating artificial intelligence tools to improve operational efficiency and analytical capacity.

The main regional challenge relates to the availability of technological infrastructure and specialized talent. However, the integration of these tools also represents an opportunity for modernising productive sectors and improving productivity.

A transformation that just begins

Generative artificial intelligence is redefining the role of technology within companies. More than a point tool, it begins to consolidate as a strategic platform capable of transforming business processes and models.

In this scenario, understanding global technological trends and anticipating their impact on the different production sectors will be increasingly relevant to organizations.

In Vipzus we accompany companies in key productive sectors to identify opportunities, strengthen their positioning and design growth strategies in increasingly competitive markets.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.