File: 22 September, 2026

The IA enters the business structure

What changes for companies according to Stanford?

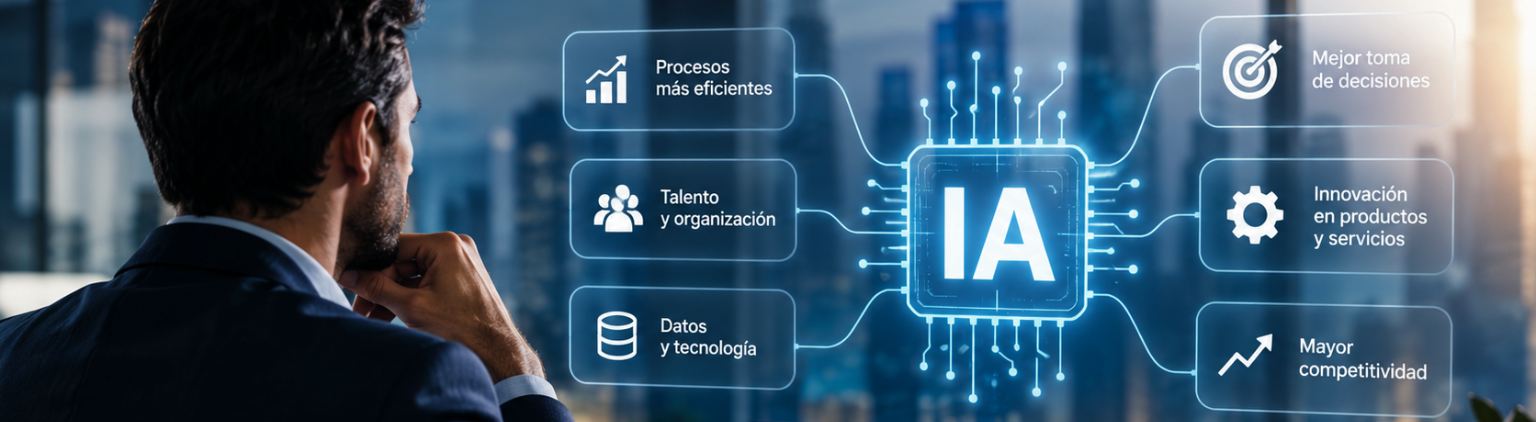
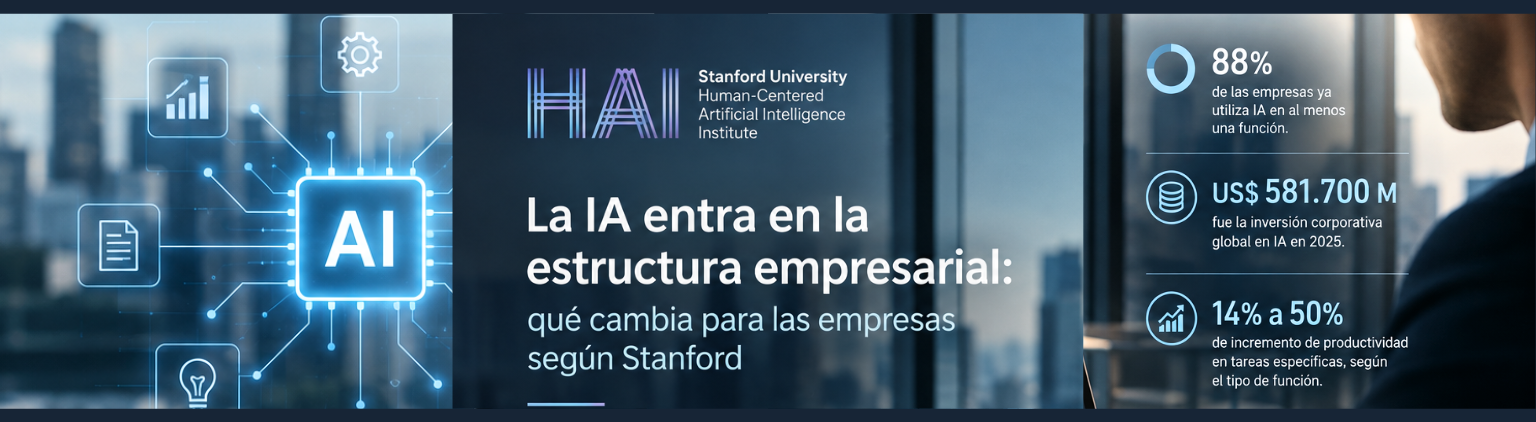
The AI Index 2026 shows that artificial intelligence became a structural place in the organizations. Business adoption reached 88%, global corporate investment reached US$581.7 billion and the first productivity effects appear more clearly in functions where work can be measured. For companies, the strategic challenge is to order where to apply IA, how to measure its impact and what internal capacities to develop.

Business adoption reached a structural scale

Artificial intelligence entered a new stage of business adoption.

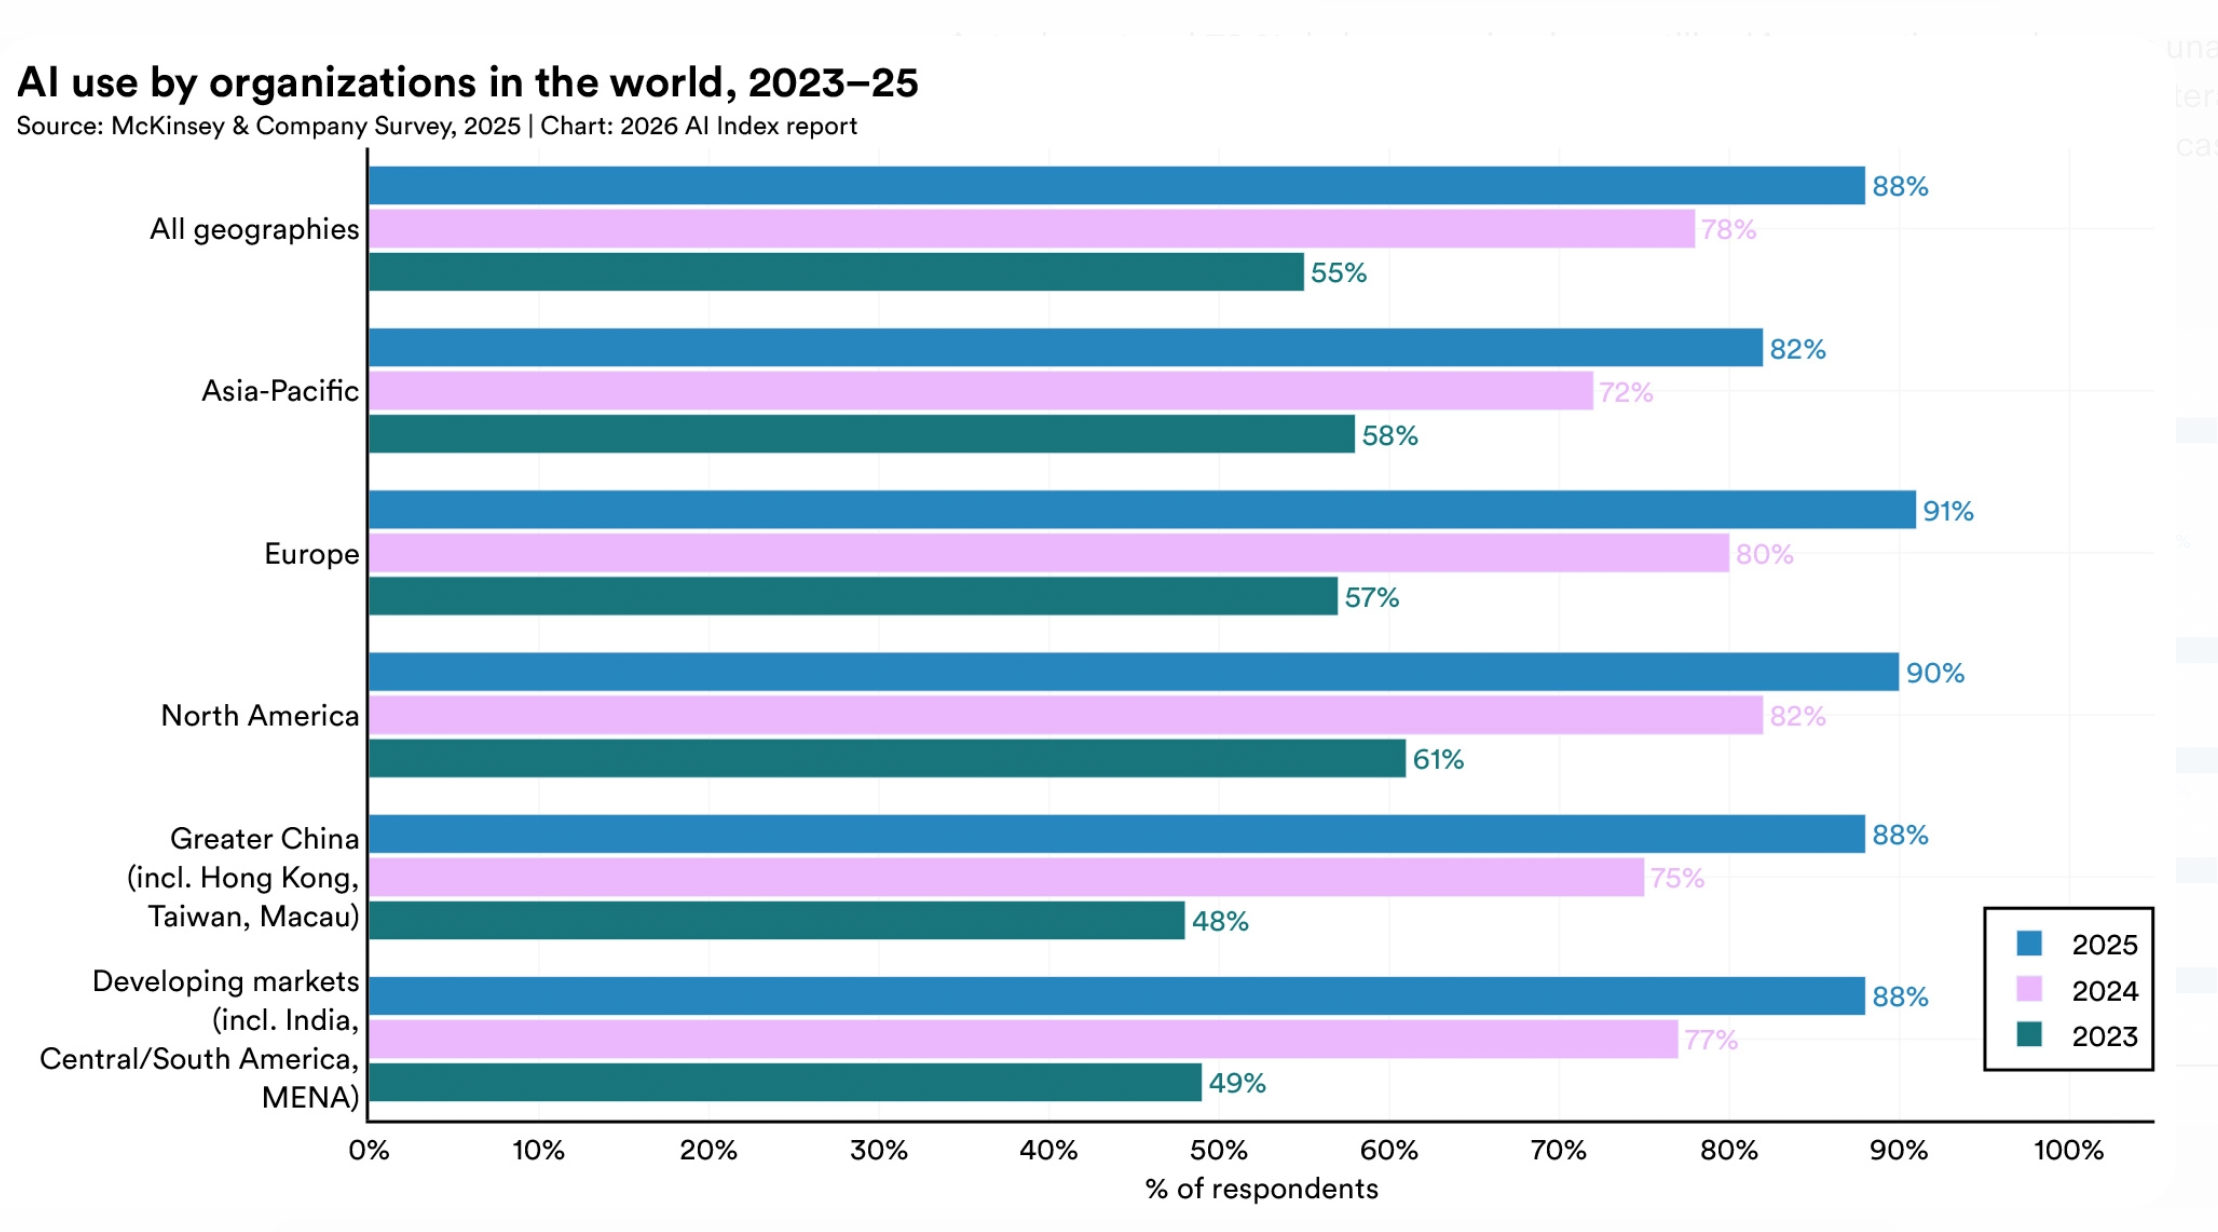
According to Stanford HAI Index 2026, 88% of the organisations surveyed reported using IA in at least one function during 2025, compared with 78% in 2025. In addition, more than half of the organizations reported using IA in three or more functions.

Generative IA also expanded its presence. 79% of the organizations surveyed reported using it regularly in at least one business function, compared with 71% of the previous year. China and Europe recorded some of the largest annual increases in adoption.

This evolution changes the business conversation. The central issue is the ability to integrate technology into specific processes, with defined economic and metric performance objectives.

For a CEO or commercial director, this involves reviewing where the IA can generate direct impact on income, costs, productivity and predictability.
Investment marks a new competitive scale

The volume of capital allocated to artificial intelligence confirms the economic dimension of this transformation.

Stanford estimates that global corporate investment in IA reached US$581.7 billion in 2025with a growth of 130% over the previous year. Private investment reached US$344.7 billion and grew 127.5%. The investment in generative IA increased by more than 200% and concentrated about half of private funding.

United States maintained a dominant position in private investment, with US$285.9 billion in 2025, compared to US$12.4 billion in China. Stanford warns that this comparison may underestimate the total volume of resources allocated by China due to the weight of public and state funds.

The investment dimension also appears in infrastructure. The major technology companies are strongly raising their capital costs to sustain computing capacity. Google, for example, reported more than US$150 billion capex per year in 2025.

For companies in other sectors, this investment scale has a specific consequence: the availability of IA tools will continue to expand and the relative cost of accessing advanced capacities will remain a strategic variable.

Productivity is beginning to be measured by function

One of the most relevant data in the report appears in the relationship between IA and productivity.

Stanford identifies increases from 14% and 15% in customer service, 26% in software development and 50% in marketing production. The greatest benefits appear in structured, measurable tasks with simple results to verify.

This point has a direct implications for management.

The productivity associated with IA can be more accurately analysed when the company breaks down its processes into specific activities. Attention to consultations, content generation, documentary analysis, programming, information classification and certain administrative tasks have favourable characteristics for this measurement.

The business decision requires identifying these functions before making extensive investments.

A company can have a high level of technological adoption and have a limited economic impact if the IA is incorporated without a precise definition of the process, indicator and expected result.

The commercial area enters a new stage of measurement

The productivity data in marketing is particularly relevant for B2B companies.

Content generation, commercial information analysis, account research, prospectus segmentation and certain commercial preparation tasks can incorporate IA tools within existing processes.

The strategic impact appears when these capabilities are connected to specific commercial variables: volume of opportunities, speed of response, cost of acquisition, account coverage, conversion and pipeline quality.

The IA can also expand the analytical capacity of commercial equipment working with large volumes of information.

The opportunity is linked to the structure of the business process. An organization with clear indicators can measure where technology generates productivity and where it requires process redesign.

Talent also begins to change

The adoption of IA has an effect on the composition of the teams.

The AI Index notes that labour impacts appear unevenly and more intensively in certain exposed groups and occupations. The use of software developers between 22 and 25 years of age fell by about 20% since 2024, while older workers experienced a different evolution. In addition, one third of the organizations surveyed expect to reduce their staff over the next year.

The data requires careful business reading.

The incorporation of IA modifies the combination of tasks, skills and professional profiles. For companies, this increases the importance of defining which functions require specialized knowledge, which activities can be automated and what new capacities must be developed internally.

Talent planning begins to be integrated with technology strategy.

Latin America faces an opportunity for selective adoption

The global expansion of the IA also opens an opportunity for Latin America.

Stanford shows that the adoption of generative IA reached 53% of the world's population in just three years. The rate of adoption has significant differences between countries and has a significant relationship with the level of income. At the same time, some markets reach higher levels than expected for their relative income.

The report also identifies Chile among the countries where IA's engineering capabilities are growing more rapidly.

For Latin American companies, this dynamic creates a scenario of increasing access to tools developed in leading markets.

The competitive advantage can arise from the ability to select applications with economic impact, integrate them into commercial and operational processes and build indicators to assess results.

The business priority goes by selecting where to capture value

Stanford's data show a simultaneous expansion of investment, adoption and productivity.

The strategic decision for companies is to translate this technological expansion into concrete priorities.

Three variables are of particular relevance:

1. Processes: identify activities where IA can generate measurable productivity.

2. Economy: to establish the impact on costs, income, margins and use of resources.

3. Structure: define responsibilities, internal capacities, indicators and investment criteria.

Technological adoption begins to form part of the business architecture. Value appears when the company can connect technology, processes and economic results within the same management logic.

The structure defines the ability to capture the value of the IA

The AI Index 2026 shows that artificial intelligence reached a significant business scale. 88% of the organizations surveyed already report some use of IA and global investment continues to grow at extraordinary rates.

For decision makers, the next challenge is linked to the ability to transform adoption into productivity, productivity into results and results into a sustainable business structure.

Artificial intelligence begins to function as a cross-sectional variable of competitiveness. Their impact will increasingly depend on the quality of the decisions accompanying their incorporation.

Vipzus accompanies in key production sectors in the diagnosis of opportunities, the management of their business structure and the definition of growth strategies. In a scenario where the IA modifies processes, capacities and investment criteria, strategic clarity takes on a central role in prioritizing opportunities and strengthening business predictability.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


The adoption of IA enters a stage of scale

Artificial intelligence is entering a stage in which the main business question goes through the ability to turn technological adoption into economic impact. The advantage begins to depend on how companies reorganize processes, talent, investment and decision-making around the IA.

The adoption of IA enters a stage of scale

Business adoption continues to accelerate. According to AI Index 2026 of Stanford, 88% of the organizations surveyed use IA in at least one function, while the generative IA is already present in at least one business function in 70%. At the same time, the use of IA agents remains at an early stage in most functions.

McKinsey finds a similar signal: almost nine out of ten participants use IA regularly in some function and 44% claim that their organization is carrying the IA on a business scale, compared to 38% of the previous year. In large companies, the proportion is 54%.

The strategic signal is clear: The IA is moving from being a tool used by individuals to becoming a capacity that begins to affect the full architecture of companies.

This movement has a direct consequence for decision makers: the relevant question goes by identifying where the IA can change revenue, costs, productivity, trade speed and decision-making capacity.

Individual productivity needs to become a business result

One of the central market tensions appears between adoption and capture of value.

McKinsey points out that companies are achieving individual productivity benefits while seeking to move them to sustainable financial results. His research suggests that the capture of value requires organizational changes that accompany the incorporation of IA.

Deloitte comes to a convergent conclusion: only 34% of the organizations surveyed claim to be really rethinking their business from the IA.

This places a strategic variable in the foreground:

The productivity generated by IA needs to be connected to specific economic indicators.

For a B2B company, these indicators may include:

  • Cost of purchasing customers;
  • Trade cycle speed;
  • Pipeline conversion;
  • Margin per client;
  • Response time;
  • Operational cost per transaction;
  • Recurrence;
  • Productivity per employee;
  • Launch speed of new services.

Technology is of business relevance when it changes these variables.

IA agents may alter the work structure

The next stage is linked to the AI agents, systems capable of performing tasks and processes with different degrees of autonomy.

McKinsey has a significant growth in the use of agents, especially among large companies: 40% of respondents from companies with incomes above US$One billion states to be climbing IA agents, compared to 27% of the previous year.

Deloitte here identifies one of the main organizational challenges. His research points out that approximately 75% of the executives consulted consider that their operating model will have to change over the next 12 to 18 months to support the expansion of IA.

The change may affect functions such as:

  • Commercial: research of prospects, preparation of proposals, monitoring and analysis of opportunities.
  • Marketing: content production, segmentation, audience analysis and customization.
  • Finance: analysis of information, forecasting and detection of anomalies.
  • Operations: planning, documentation, coordination and impact management.
  • Technology: software development, testing, documentation and maintenance.

The strategic consequence is relevant: the company begins to need a work architecture where intelligent people and systems share tasks, information and decisions.

The real challenge appears in the processes

Deloitte identifies one of the main barriers to scaling agents: organizations often try to automate processes originally designed for people. His report claims that only 11 per cent of organizations had successfully deployed IA agents in production at the time of their investigation.

This has a direct reading for the business strategy.

A fragmented business process, for example, can be partially automated by IA. Automation can accelerate individual tasks while maintaining the original structure of a process that has multiple friction points.

The opportunity appears when the company first analyses:

  1. What process generates value;
  2. Where repetitive work is concentrated;
  3. What decisions require a human approach;
  4. What information is available;
  5. What tasks can be delegated to systems;
  6. What indicators can measure the result.

This diagnosis makes it possible to define where the IA has a real capacity to generate impact.

Investment in IA increases and also increases the demand for return

Global investment confirms that transformation has a growing economic dimension.

Stanford estimates that global corporate investment in IA more than doubled during 2025. Private investment grew 127.5%, while generative IA concentrated almost half of the private funding related to IA.

This expansion is also increasing expenditure on infrastructure. Companies need computer capacity, storage, data, security and technological architecture to sustain increasing IA loads.

Deloitte warns that the increase in use can exceed the reduction in unit processing costs, creating increasing pressure on infrastructure and technology budget.

This is why a new management variable appears:

The return on investment in IA needs to be assessed at process and economic unity level.

Governance becomes a business variable

The progress of self-governing actors also increases the importance of governance.

Deloitte points out that only one in five companies has a mature model of governance for self-employed actors.

The challenge involves:

  • Access to sensitive information;
  • Permissions;
  • Tracability;
  • Security;
  • Human monitoring;
  • Protection of intellectual property;
  • Regulatory compliance;
  • Responsibility for automated decisions.

The regulatory discussion is also gaining intensity. In the United States, for example, legislators are driving new security rules and controls for advanced IA systems.

For companies, this makes IA governance a strategic management dimension linked to risk, reputation and operational continuity.

Latin America can capture value from business efficiency

For Latin America, the scenario presents an opportunity especially linked to productivity.

Companies in the region operate in markets where trade efficiency, the availability of specialized talent and the scale can condition growth. The IA can reduce certain information costs, speed up processes and allow relatively small teams to manage more activity.

The strategic point is in the selection of use cases.

Companies can prioritize applications related to:

  • Demand generation → identification and prioritization of prospects.
  • Sales → pipeline analysis, proposals and follow-up.
  • Service → automation of queries and classification of requirements.
  • Operations → planning, documentation and coordination.
  • Address → information analysis and decision support.

This logic is particularly relevant for B2B companies, where the quality of the business process is directly related to predictability and revenue.

The competitive advantage begins to depend on the reorganisation capacity

The evidence available points to the same direction: the adoption of IA grows rapidly, as organizational transformation advances at a more heterogeneous rate.

McKinsey notes that organizations are moving towards a larger scale of implementation. Deloitte simultaneously identifies a gap between strategic and operational preparation.

For CEOs and business directors, this puts five decisions at the heart of the agenda:

  • 1. Prioritize processes with measurable economic impact.
  • 2. To define which tasks remain under human responsibility.
  • 3. Build a data architecture to scale IA.
  • 4. Measure economic return by use.
  • 5. Design a commercial and operational structure prepared to work with intelligent systems.

The business transformation led by IA begins to acquire a structural dimension. Technology is a part of change. The organization, processes, talent, investment and indicators determine the ability to capture value.

The strategic agenda for the next 12 to 24 months

For business decision makers, the agenda can be organized around four questions:

Where it generates value the IA.
Identify processes where there is a clear relationship between automation, productivity and economic impact.

What structure the company needs.
Review internal processes, responsibilities, technology and capacities.

What investment each initiative requires.
Measuring infrastructure, talent, integration, security and recurrent costs.

How the result will be measured.
Link each implementation with income, margin, productivity, speed or predictability.

The IA is moving towards a phase in which business transformation capacity begins to be as relevant as technological capacity. Organizations that develop mechanisms to convert smart tools into measurable business improvements will be better prepared to capture the economic value of this new stage.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Profitability of business

Does your business structure drive growth or limit business profitability?

The expansion of the health and beauty market opens up new opportunities for companies with a business structure capable of transforming demand into sustainable income.

The commercial organization takes a decisive role in capturing value in an environment where competition increases, channels multiply and the consumer increases its expectations.

Market growth requires increased trade capacity

The health and beauty sector maintains a growth dynamic driven by the demand for well-being, prevention, personal care and increasingly personalized solutions. The incorporation of artificial intelligence, diagnostic tools and omnicanal models expands the possibilities of interaction with the customer and accelerates the emergence of new competitors.

This scenario increases commercial complexity. The availability of products is no longer the main competitive factor. The ability to reach the right customer, develop long-term relationships and manage a cost-effective portfolio becomes more relevant to sustain growth.

Profitability depends on the quality of the commercial portfolio

Many companies concentrate their income on few distributors, chains or historical customers. This configuration generates financial exposure, reduces negotiating power and conditions expansion capacity.

The commercial structure allows the portfolio to be balanced by more precise segmentation, the incorporation of new channels and the development of proposals adapted to different customer profiles.

Each segment has different needs, purchase cycles and profitability levels. An organized trade strategy facilitates the efficient allocation of resources and the prioritization of opportunities with greater economic impact.

The expansion of channels requires strategic coordination

The growth of e-commerce, specialized clinics, pharmacies, marketplaces and hybrid experiences expands the alternatives to reach the final consumer. At the same time, it increases the need for coordination between marketing, sales and customer service.

A strong trade structure defines specific objectives for each channel, sets performance indicators and avoids overlaps that affect margins or generate trade conflicts.

Predictability also improves when there is clarity about the contribution of each channel to the overall outcome of the business.

Data strengthen commercial decision-making

The digitization of the sector generates an increasing volume of information on consumer habits, recurrence, purchasing behaviour and customer preferences.

Transforming such data into commercial decisions represents a competitive advantage. Prioritization of opportunities, efficient allocation of commercial equipment and identification of segments with greater potential strengthen profitability and reduce uncertainty.

Commercial intelligence becomes a strategic asset for companies that seek to sustain growth in dynamic markets.

The trade structure provides financial predictability

Sustainable growth requires an organized trade base.

A defined structure makes it possible to project revenue, measure the performance of the pipeline, anticipate changes in demand and improve financial planning.

Trade indicators no longer reflect only historical results and become tools for future decision-making.

This capacity strengthens investment, facilitates territorial expansion and improves adaptation to market changes.

A strategic agenda for sector decision-makers

Business directors and CEOs in the health and beauty sector find concrete opportunities when reviewing key questions:

  • Does the client portfolio reflect the real potential of the market?
  • Does each channel provide sustainable profitability?
  • Does the commercial organization allow it to grow with predictability?
  • Do the available indicators provide strategic decisions?
  • Does the current structure accompany consumer and market developments?

To answer these questions allows to identify opportunities for improvement with direct impact on income, margins and competitive positioning.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Customers, channels or markets

What risk does it pose for your company to depend on the same customers, channels or markets as usual?

The expansion of the technology sector maintains a sustained pace driven by artificial intelligence, automation and digitization of business processes.

In this scenario, many technology companies continue to grow on a commercial basis concentrated on a small set of customers, procurement channels or geographical markets. This concentration conditions business stability and limits the ability to sustain growth in the medium term.

Technology companies often develop long-term relationships with strategic customers. This model provides recurrent income and strengthens sectoral experience. At the same time, it increases exposure to any change in investment priorities, budgets or strategies of such clients.

Trade concentration increases business vulnerability

A concentrated portfolio amplifies the financial impact of each decision made by a relevant client. The cancellation of a contract, the reduction of the technological budget or a change of supplier may affect revenue, cash flow and investment capacity in innovation.

This scenario also conditions financial planning. Predictability depends on a limited number of external decisions, making it difficult to project growth more stable.

Traditional channels reach a point of maturity

Many technological companies built their growth through references, personal networks or historical alliances. These channels maintain strategic value, although they have limits to support expansion processes.

The B2B purchase process evolves towards digital routes where buyers investigate suppliers, compare solutions and use artificial intelligence tools to evaluate alternatives before first commercial contact. Visibility in different channels begins to directly influence the generation of opportunities.

Organizations that develop multi-channel strategies strengthen their ability to capture demand from different points of contact and reduce the dependence on a single business source.

Diversification strengthens trade predictability

Diversifying means expanding the commercial scope through new segments, industries, regions or marketing models. This strategy distributes risk and generates a more balanced income structure.

The incorporation of new markets also provides valuable information on emerging needs, strengthens innovation capacity and expands the competitive potential of the company.

Technology companies with structured business processes have better tools to identify opportunities, prioritize investments and manage sales cycles more accurately.

Expansion requires structure and priority criteria

Entering new markets requires informed decisions. The selection of segments, the value proposal, the commercial capacity and the resources available determine the feasibility of each initiative.

Sustained growth depends on a diagnosis to identify where there is the greatest potential for profitability, which channels have the best prospects and which customers contribute to building a more balanced portfolio.

The organizations that incorporate these criteria strengthen their resilience to economic, technological and competitive changes.

Strategic direction defines growth capacity

The development of the technological market increases the importance of regular review of the composition of the client portfolio, income distribution and the diversity of commercial channels. This assessment allows for the identification of concentration levels that could limit the future development of the company.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Lead companies

Are the companies that will lead the energy sector in five years already making decisions that your organization still postpones?

Energy industry leaders build their competitive position through long-term decisions.

The current context combines electrification, digitization, regulatory pressure, new technologies and a growing demand for critical infrastructure. Each of these variables requires a strategic vision capable of anticipating scenarios and allocating resources with economic sustainability criteria.

Decision speed becomes a competitive advantage

Energy investment cycles require years of planning and implementation. Each decision related to infrastructure, generation, storage, digitization or commercial expansion conditions the ability to compete over the next decade.

Fast-moving organizations strengthen their position in an environment where demand evolves faster than installed capacity. Strategic planning takes on a central role in prioritizing investment and reducing uncertainty.

Energy infrastructure incorporates new competitiveness criteria

The expansion of electricity networks, storage systems and the integration of renewable energy sources concentrate much of global investment. At the same time, sectors such as industry, electricity mobility and data centres increase their demand for reliable and flexible supply.

This scenario drives a profound transformation in the allocation of capital. Companies that develop capacities to operate in more complex energy ecosystems strengthen their resilience and expand their growth opportunities.

Digitization accelerates operational efficiency

Artificial intelligence, advanced analytics and real-time monitoring systems make it possible to optimize assets, anticipate failures and improve energy demand management. These tools increase operational availability and provide greater financial predictability.

The incorporation of these capacities represents a strategic decision directly linked to productivity and future profitability.

Strategic partnerships expand growth capacity

The development of energy projects involves manufacturers, operators, technological developers, financial institutions and regulatory bodies. Building strong partnerships facilitates access to innovation, financing and new markets.

Organizations that strengthen strategic relationships strengthen their capacity to implement larger-scale projects and respond more agile to changes in the environment.

Trade planning takes a leading role in the sector

Energy competitiveness also depends on the ability to identify more valuable segments, develop new markets and build differentiated proposals for industrial, corporate and institutional customers.

The business structure becomes relevant as a tool to generate predictability, diversify income and sustain expansion processes with cost-effectiveness criteria.

Postponed decisions generate increasing costs

Each deferred project involves a reduced capacity to capture future opportunities. Organizations that delay the incorporation of technology, the modernization of assets or the revision of their trade strategy face greater challenges in adapting to an increasingly dynamic market.

The competitiveness of the energy sector depends on consistent decisions, long-term vision and the ability to anticipate structural changes that are already being consolidated.

The companies that will lead the market over the next five years are today building the capacities that will support their growth, strengthen their positioning and improve their response capacity to a permanent transformation environment.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Strategic logistics decision

What strategic decision is holding back the growth of your logistics company without you detecting it?

In logistics, growth is usually measured by the volume transported, the number of customers incorporated or the territorial expansion.

However, many companies find that these indicators coexist with stagnant profitability, increasing pressure on margins and a trade structure that loses the capacity to generate value.

Trade homogeneity reduces growth potential

Many logistics companies offer the same business scheme for industries, company sizes and completely different needs. This decision simplifies the commercial operation, but also limits the ability to capture value.

The pharmaceutical, food, energy, industrial or technological sectors demand different levels of traceability, response times, regulatory compliance and operational availability. Each segment perceives value differently.

Companies that develop specific proposals for each customer profile strengthen their positioning and generate longer-term business relationships.

The price concentrates low-return competition

Competitive pressure drives tariff-focused negotiations. This dynamic reduces margins and makes it difficult to sustain investment in technology, infrastructure and trade development.

Organizations that build advantages based on operational visibility, technological integration, data intelligence and anticipation capacity expand their market differentiation.

Recent developments in international trade confirm that supply chains value suppliers that can respond flexibly to regulatory changes, logistical interruptions and changes in demand.

The composition of the portfolio defines future profitability

Sustained growth depends on the quality of the commercial portfolio.

A high concentration in few customers increases financial exposure. A portfolio of low-margin operations limits investment capacity. An expansion based only on new contracts incorporates volume, but can also increase operational complexity without improving results.

The most predictable companies analyse profitability by segment, identify higher value-added opportunities and allocate commercial resources according to the strategic potential of each market.

Commercial intelligence takes on a central role

Digitization transforms logistics into an activity with greater analytical capacity.

Artificial intelligence, predictive analysis and real-time monitoring tools strengthen route planning, inventory management and risk anticipation. Its impact also reaches the commercial strategy by facilitating a better understanding of the behaviour of customers and the evolution of each segment.

Information makes it possible to prioritize opportunities with greater cost-effectiveness potential and to focus trade decisions on measurable objectives.

The strategic direction determines the speed of growth

Logistic companies operate in a market where complexity continues to increase. The expansion finds better results when it responds to a clear strategy of positioning, segmentation and trade development.

The periodic review of strategic decisions makes it possible to detect restrictions that often remain invisible within the day-to-day operation. This capacity strengthens predictability, improves income quality and expands the potential for sustainable growth.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Regenerative agriculture

Regenerative agriculture: the new competitive border of agro-industrial chains

regenerative agriculture ceased to occupy a peripheral place on the sustainability agenda to become a strategic variable of global agro-industrial chains.

Large food companies, retailers and agricultural traders are incorporating criteria related to soil health, carbon capture and environmental traceability as part of their supply policies.

This movement responds to a combination of economic, regulatory and commercial factors. The pressure to reduce emissions, increasing consumer demand for products with verifiable environmental attributes and the need to strengthen productive resilience are accelerating the transformation of the sector.

For agribusiness, the phenomenon transcends the environmental dimension. Regenerative agriculture is beginning to influence market access, financing conditions and the ability to capture more value within the chain.

Sustainability gains weight in global purchase decisions

Leaders in the food sector are promoting regenerative supply programmes in many regions of the world. The objective is to improve environmental indicators and strengthen the long-term stability of agricultural production.

The European Union is making progress in regulations linked to sustainability and traceability. Several international markets incorporate environmental metrics into their purchase and investment processes. This scenario drives a growing demand for verifiable information on productive practices.

The ability to demonstrate origin, soil management and environmental footprint is of commercial relevance. Certification and monitoring systems begin to form part of the competitive infrastructure of the agro-industrial business.

Soil health impacts on productivity and resilience

Extreme climate events increased attention to the ability of agricultural systems to sustain returns in higher volatility scenarios.

Regenerative practices include crop rotation, cover crops, reduction of labour and integrated management of natural resources. These strategies help to improve soil structure, increase water retention and strengthen biodiversity.

Productive resilience becomes an economic variable. Producers developing more stable systems can improve predictability and reduce exposure to climate risks.

In markets with growing uncertainty, productive stability strengthens business competitiveness.

Carbon markets open new income opportunities

The expansion of voluntary carbon programmes generates new monetization alternatives for the agricultural sector.

Various international initiatives seek to measure and pay for agricultural practices that contribute to carbon capture in the soil. The development of standardized methodologies and verification systems drives the growth of these markets.

The generation of complementary income still presents technical and regulatory challenges. However, the interest of investors, food companies and financial actors continues to grow.

The ability to generate verifiable environmental assets can become a relevant component of future profitability.

Digital traceability strengthens value capture

The expansion of regenerative agriculture drives investments in monitoring technologies, sensors, satellite images and digital platforms.

Data take on a central role in documenting productive practices and responding to customer and investor requirements.

Digitization allows the construction of reliable environmental performance information and facilitates integration with global supply chains.

Agro-industrial companies that develop analytical capabilities and traceability systems will be better positioned to capture new business opportunities.

The commercial structure defines the ability to capture value

The transition to regenerative models expands the complexity of the agro-industrial business. Economic value begins to be distributed between production, certification, financing, data and market access.

Many companies maintain strong dependence on intermediaries and face difficulties in capturing some of that additional value.

The construction of direct trade relations, the development of traceability capacities and channel diversification emerge as strategic factors for strengthening income and predictability.

Market developments indicate that future competitiveness will increasingly depend on the ability to integrate production, information and trade strategy.

regenerative agriculture is moving forward as a new standard of global competitiveness. Its impact reaches productivity, financing, positioning and market access.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Fall from the chain market

How much money does a company lose when it competes for price only?

Discount-based competition generates a direct transfer of profitability to the customer, weakens investment capacity and reduces trade differentiation.

In consumption and retail, the cost of this strategy often appears well before the fall in sales.

The margin finances business growth

In consumption and retail, each percentage point of margin represents the ability to invest in marketing, technology, purchasing experience, training of commercial equipment and channel expansion. When a company systematically reduces prices to win operations, it also reduces the resources available to strengthen its competitiveness.

The consequence appears gradually. The business sells more units, although it generates less profitability per transaction. This dynamic requires a growing volume to sustain the same level of financial results, increasing the pressure on the entire operational structure.

Price competition changes consumer behaviour

Today's consumers have more information, compare real-time options and take advantage of promotions in an increasingly planned way. Several studies show that a significant part of the purchases are organized around discounts and temporary benefits, strengthening a very price-sensitive demand.

This scenario generates a structural effect: the customer incorporates the discount as a permanent reference. The purchase decision loses stability and increases the dependence on continuous promotions.

The hidden cost of reducing prices

The economic loss associated with competing for price only rarely appears in a single indicator. It is distributed in different dimensions of the business:

  • Lower gross margin per operation.
  • Increased need for volume to achieve the same economic result.
  • Reduction of available resources for innovation and trade development.
  • Increase in permanent promotions.
  • Reduced capacity to build a differentiated value proposal.
  • Increased sensitivity to new competitors.

Each of these variables reduces the company's financial resilience to demand changes or cost increases.

The market rewards the value proposal

Companies with better retail performance combine commercial variables that go beyond the price. The purchase experience, product availability, logistics speed, personalized care, loyalty programs and brand positioning strengthen the consumer's willingness to choose a company even if there are cheaper alternatives.

The commercial strategy incorporates customer segmentation, cost-effectiveness analysis by category and intelligent portfolio management. This combination allows the margin to be protected without losing competitiveness.

Price as a strategic tool

The price maintains a central role within any commercial strategy. Its impact depends on the context, product category, target segment and company positioning.

The most competitive organisations use differentiated price policies according to specific objectives:

  • New client capture.
  • Inventory rotation.
  • Launch of categories.
  • Channel development.
  • Development of strategic segments.

Each decision responds to previously defined financial and trade indicators.

Profitability depends on comprehensive decisions

Sustainable growth comes from a balanced combination of price, value proposal, operational efficiency and customer knowledge.

In a context where consumers are increasingly comparing alternatives and promotions are increasingly placed within mass consumption, the ability to preserve margins becomes a competitive advantage. Companies and supermarkets deepen promotions to sustain sales, although this dynamic also increases the need to review the profitability of each commercial action.

The question relevant to directories stops focusing only on how much to sell and is directed towards how much value each sale generates for business.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


Mass hearing

The monetization of digital communities transforms the content industry

The global media and entertainment industry is undergoing a profound transformation in how to build value, attract attention and monetize content.

Mass audiences continue to take a scale, although economic growth in the sector is beginning to focus on community-based models, affinity and sustained engagement.

The change impacts directly on platforms, traditional media, producers, brands and companies linked to the advertising business.

The creative economy advances over segments historically dominated by large media groups. YouTube, Twitch, TikTok, Discord and live content formats consolidate an ecosystem where closeness with the audience generates more stable competitive advantages than traditional mass reach.

The phenomenon begins to modify monetization structures, advertising investment and digital positioning construction.

The fragmentation of consumption changes the rules of the audiovisual business

For decades, the media industry built scale from audience concentration. Open television, cable and large digital platforms organized business models supported in volume and mass distribution.

The expansion of social platforms altered that logic.

Current digital consumption is organized around specific interests, thematic communities and permanent relationships between creators and audiences. Sports, game, finance, lifestyle, technology and entertainment develop niche ecosystems with high levels of interaction.

The length of stay begins to have greater economic weight than the overall scope.

YouTube already represents one of the main global destinations of audiovisual consumption and strengthens leadership in the face of traditional streaming platforms. According to Nielsen, YouTube maintains one of the largest shares of television consumption connected in the United States during 2026, driven by creators and hybrid content between entertainment and community.

The economic impact is direct. The brands find more segmented, more precise metric audiences and potentially more efficient acquisition costs.

Monetization turns to models based on engagement and recurrence

Digital advertising goes through a transition oriented to quality of interaction and ability to influence.

Digital communities generate more frequent relationships, longer exposure time and higher levels of confidence compared to traditional advertising formats.

This scenario strengthens:

  • Subscriptions.
  • Membresies.
  • Exclusive content.
  • Live commerce.
  • Ssegmented Sponsorships.
  • Direct monetization of hearing.

The creator is no longer just a content producer. It begins to play a role similar to that of a specialized vertical environment with the capacity to mobilize specific communities.

Twitch, Patreon, YouTube Memberships and Discord accelerate models where the recurrence of income depends on loyalty and depth of the link with the audience.

The economic logic of the sector begins to move from the volume of impressions to community quality.

Media companies face pressure on their traditional structure

Traditional media groups are under increasing pressure on costs, monetization and retention of young audiences.

The growth of independent creators reduces entry barriers and multiplies content supply. Competition is no longer organized only between large companies.

The strategic challenge appears in the ability to build identity, differentiation and formats capable of sustaining attention in hyperfragmented ecosystems.

Audiences consume content on multiple platforms simultaneously:

  • Short clips.
  • Streaming live.
  • Podcasts.
  • Newsletters.
  • Video on demand.
  • Interactive content.

The distribution loses centrality as an exclusive competitive advantage.

The capacity to build community acquires greater economic and strategic value.

Various media groups begin to incorporate external creators, alliances with influences and collaborative formats to strengthen engagement and expand digital monetization.

The movement also impacts on commercial and advertising structures. The brands demand metrics linked to real interaction, loyalty and conversion.

Artificial intelligence amplifies competition for attention

Artificial intelligence accelerates large-scale content production, editing and adaptation. This expansion increases the volume of publications and deepens digital saturation.

In this context, the community is beginning to function as a competitive barrier.

The creators with fidealized audiences maintain the ability to sustain traffic, conversation and monetization even in environments with oversupply of automated content.

The perceived authenticity, constant interaction and sense of belonging strengthen the economic value of digital communities.

The impact also reaches companies outside the media sector.

Retail, technology, education, gaming and mass consumption begin to develop strategies focused on building their own community to reduce advertising dependence and strengthen direct relationships with customers.

Latin America accelerates the adoption of creative-based models

The region shows sustained growth in digital consumption, online video and creative economy.

Brazil, Mexico and Argentina concentrate an important part of the regional expansion of streaming, games and social platforms.

The phenomenon creates new opportunities for:

  • Producers.
  • Agencies.
  • Technology platforms.
  • Marks.
  • Digital media.
  • Advertising companies.

There are also challenges linked to monetization, regulation, intellectual property and dependence on global platforms.

Regional competitiveness is beginning to depend on the capacity to build communities with clear identity and sustainable monetization models.

Strategic value migrates to the direct relationship with the audience

The media and entertainment industry enters a stage where care is distributed among thousands of active and highly segmented communities.

The growth of the sector begins to depend less on a general scale and more on the depth of the link with the audience.

Community building emerges as one of the most relevant strategic variables for means, platforms and brands that seek income predictability and sustainable differentiation.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.


The visibility of the supply chain has an influence on logistical competition

The visibility In real-time supply chain is of strategic relevance in a market where information impacts on the profitability, confidence and continuity of contracts.

Logistics is undergoing a transformation driven by a growing demand for information. Industrial companies, retailers, e-commerce companies and organizations with complex operations incorporate new criteria for assessing their logistics suppliers. Among them, the ability to provide full visibility on the status of shipments, inventories and operational processes is increasingly relevant.

For years, operational efficiency concentrated much of the sector's attention. Traditional indicators linked to costs, delivery times and operational capacity remain critical. However, competitive dynamics incorporate a new variable: the quality of information available to the customer.

The visibility of the supply chain thus becomes a commercial asset with direct impact on loyalty and growth.

Information acquires economic value within the logistics proposal

Supply chains operate in environments characterized by greater volatility, stricter compliance requirements and increasing operational complexity.

In front of this scenario, customers seek to reduce uncertainty. The ability to know in real time the location of a load, anticipate deviations, monitor inventories or access to operational reports strengthens planning capacity and improves decision-making.

The information ceases to function only as an operational support and becomes part of the commercial value proposal.

Studies by international consultants such as McKinsey, Gartner and Deloitte show that organizations with higher visibility about their logistics operations are able to improve service indicators, optimize inventories and reduce costs associated with supply chain interruptions.

The business consequence is clear: customers assign economic value to the ability to access accurate and timely information.

Competitive pressure drives new service standards

The growth of e-commerce, the digitization of business processes and the expansion of monitoring platforms generate increasing expectations.

Corporate customers compare the logistical experience with the levels of visibility they find in other digital sectors. The permanent availability of information is gradually incorporated as a basic market expectation.

This changes the criteria for the evaluation of suppliers.

Timeliness remains important. The ability to report, anticipate and communicate acquires an equivalent relevance within the selection and stay processes of customers.

Logistic companies that offer monitoring platforms, custom dashboards, automatic alerts and integral traceability strengthen their positioning against competitors who compete mainly for price.

Tracability strengthens strategic accountability

Competition for tariffs creates constant pressure on the margins of the sector.

In this context, the construction of sustainable trade relations is increasingly dependent on the ability to generate perceived value.

Tracability contributes directly to this objective.

When a client can monitor critical operations, access historical information and have reliable indicators to manage his business, the business relationship becomes more strategic.

The conversation stops focusing exclusively on operational costs and begins to incorporate variables linked to planning, control and response capacity.

This change strengthens the permanence of strategic accounts and expands the possibilities of commercial expansion within existing customers.

Technological integration accelerates a new stage of differentiation

The expansion of Internet-related technologies of Things (IoT), intelligent sensors, artificial intelligence and data analysis platforms facilitates the construction of more transparent logistics models.

Technological investment is increasingly justified by commercial growth and customer retention.

Continuous data capture allows for the detection of incidents, the creation of early warnings and the construction of operational indicators with a level of detail higher than was available a few years ago.

Organizations that manage to integrate these capacities strengthen their capacity to respond to disruptive events and improve the experience of their clients.

The differentiation then arises from the ability to transform operational data into information relevant to decision-making.

The strategic challenge is to turn data into a competitive advantage

The availability of technology alone does not guarantee results.

Many organizations incorporate digital tools without a clear strategy to transform information into commercial value.

The competitive advantage appears when data can improve predictability, strengthen customer relationships and facilitate business decisions.

The challenge for logistics leaders is to identify which information generates value for each client segment and how to integrate it into a consistent service proposal.

Visibility becomes strategic when it helps to improve income, strengthen profitability and consolidate long-term relationships.

Visibility is incorporated into the core of logistics competitiveness

The evolution of supply chains shows a clear trend: operational transparency gains prominence in the factors that determine the competitiveness of the sector.

Logistic companies that develop traceability, monitoring and intelligent information management capabilities strengthen their position against increasingly demanding customers.

The next stage of growth of the sector will be associated with the ability to combine operational efficiency, data intelligence and customer experience within an integrated value proposal.

Slide

Evaluate a commercial diagnosis

Identify blocks and real opportunities for growth.